

Disclaimer: The following write-up is no investment advice. The author may own, buy and sell securities mentioned in this post. Please always do your own due diligence! This company is a micro-cap. Keep in mind that even a small investment from your side can move the share price due to the low liquidity of shares. It’s not easy to liquidate if you want to get out.
Welcome,
in this issue of Under-Followed-Stocks, I will present you Circle Group SpA ($CIRC.MI).
Investment Summary:
Mission-critical niche software embedded in European port and customs digitalization
Regulation-driven demand creates structural tailwinds
Positioned at the core of Europe’s logistics digitalization push, thanks to a deep integration with public institutions & EU strategy
Gradual shift toward recurring and usage-based revenues, allowing higher margins and more predictable revenues
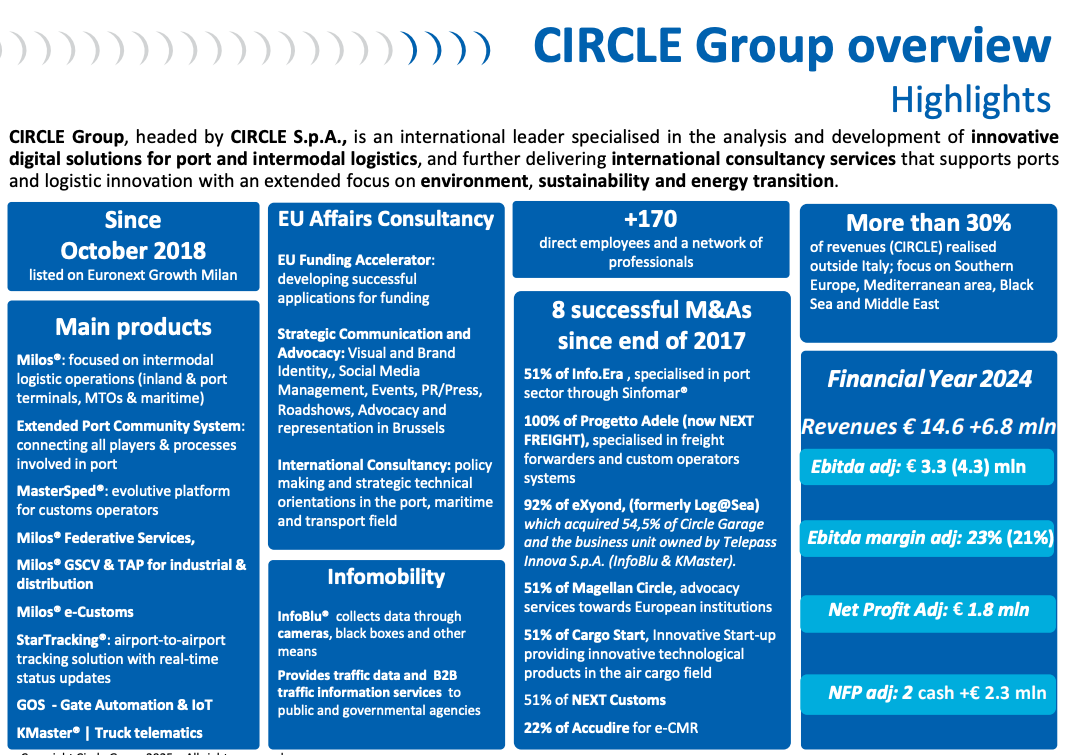
Revenue CAGR of 25% since 2012
Organic growth combined with a systematic M&A strategy
EV/EBITDA of 6.7x and EV/EBIT of 13.1x
Under-followed Italian micro-cap with limited analyst coverage & low free float
If you aren’t a subscriber yet and enjoy the content I share, feel free to subscribe so that you won’t miss any new content. The company write-ups I share are free. But if you want to keep up-to-date about the companies in my portfolio, you can voluntarily choose the paid option :)
Let’s go!
1. Introduction
Circle SpA is a small Italian-listed company operating in a part of the economy that rarely attracts investor attention: the digital infrastructure behind ports, intermodal transport, and complex logistics chains. While the sector itself is unglamorous, it plays a critical role in how goods move across Europe and how efficiently, transparently, and sustainably they do so.
The company provides mission-critical software platforms and advisory services that help ports, terminals, freight forwarders, shippers, and public institutions replace fragmented, paper-based processes with integrated digital systems. Circle’s solutions sit deep within customer workflows, often touching regulatory, customs, and operational processes that are difficult to change once implemented, even with the help of AI. Circles solutions are used by large customers like IKEA as well as multiple ports, airports or freight forwarders.
Circle Group is active in a narrow niche with high entry barriers, sticky customers, structural tailwinds from regulation and digitalization and a business model that is gradually shifting toward more recurring and scalable software revenues.
Circle Group SpA has been listed on the Euronext Growth Milan since October 2018 under the ticker $CIRC.MI. The current market cap is EUR 43 million (USD 51 million).
2. The Company
Circle SpA was founded in 2012 in Italy with a clear focus on the digitalization of logistics processes, initially concentrating on ports and maritime transport. At the time, many European ports and logistics hubs were still operating with fragmented IT systems and paper-based workflows, despite increasing regulatory and operational complexity.
In its early years, Circle positioned itself as a specialized software and consulting partner for port authorities, terminal operators, and logistics stakeholders. Rather than offering generic IT solutions, the company focused on building domain-specific platforms that could handle the coordination between private operators and public institutions, particularly in regulated environments.
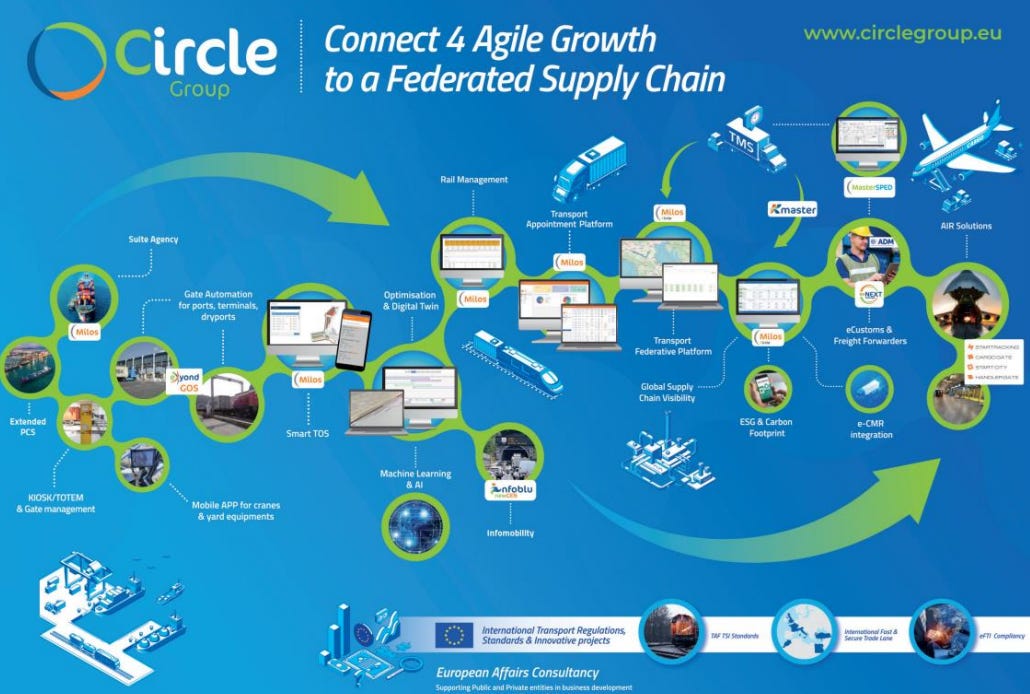
A first important milestone was the development of the Milos® platform, which became the technological foundation for Circle’s activities in ports, intermodal hubs, and logistics nodes. Over time, Milos evolved into a modular suite addressing planning, coordination, tracking, and optimization across different transport modes.
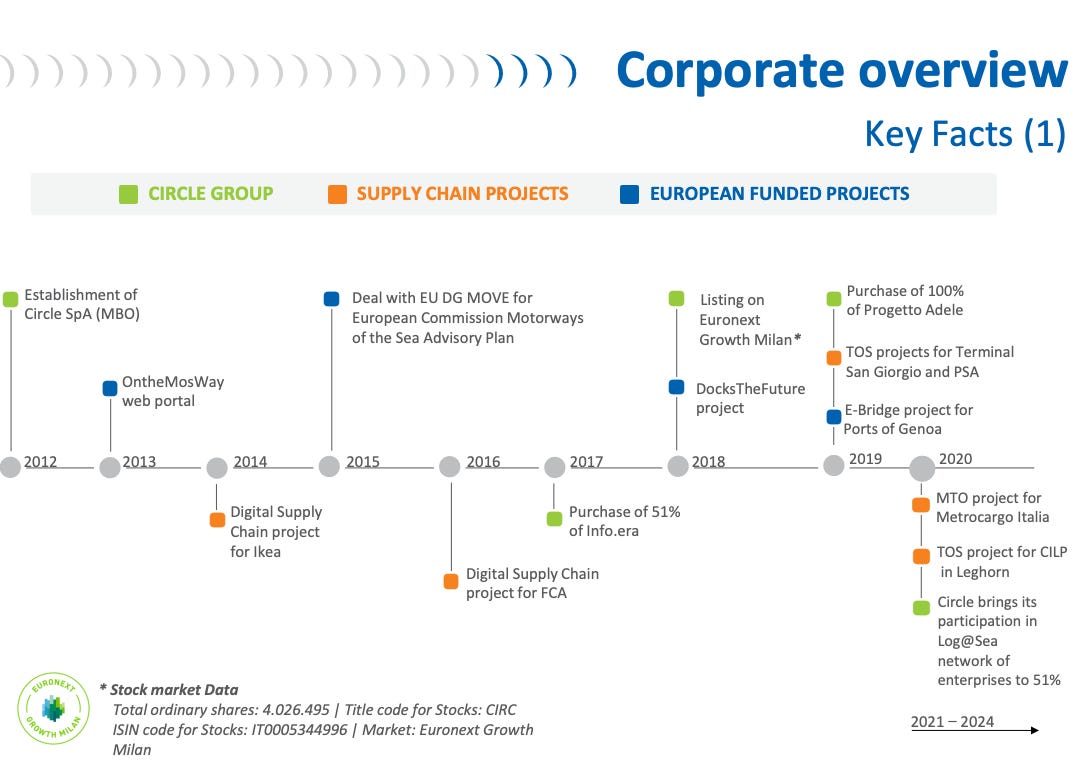
From 2017 onwards, Circle began to broaden its scope beyond purely port-centric solutions. This expansion accelerated around the time of the company’s IPO on the Euronext Growth Milan exchange in 2018, which provided additional capital to support both organic development and acquisitions.
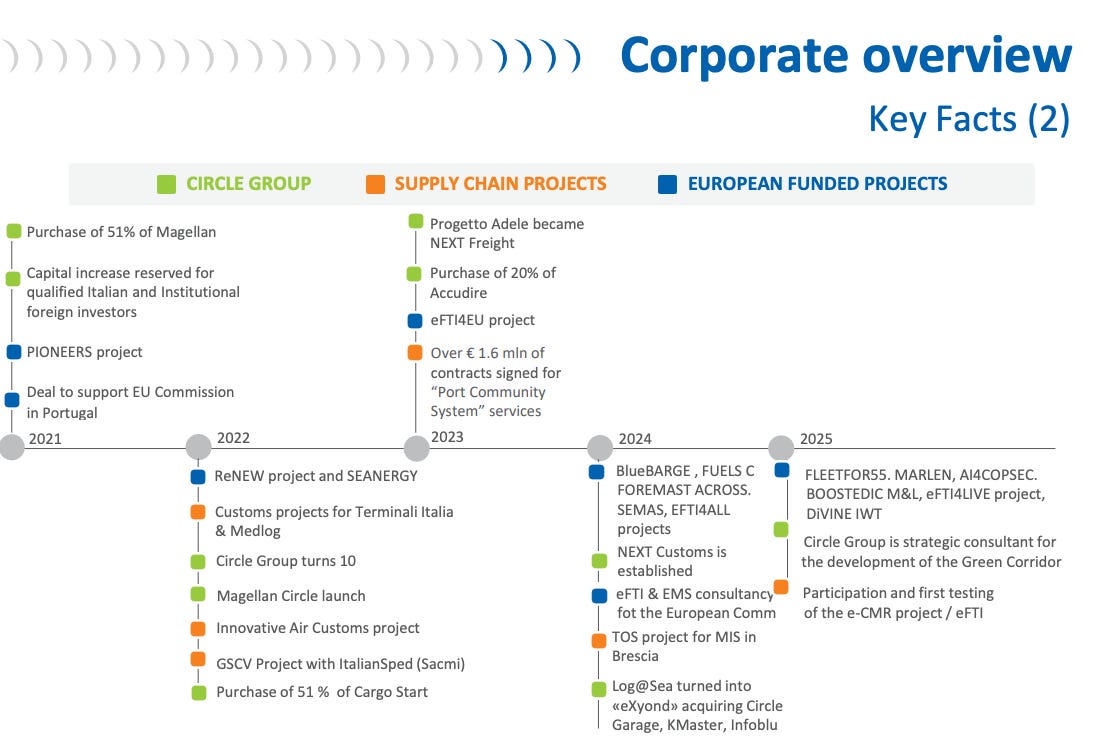
Key acquisitions followed in the subsequent years:
Info.Era (2017, 51%), specialised in the port sector through Sinfomar software
Next Freight / Progetto Adele (2019, 100 %), specialised in freight forwarders and customs operator systems
Magellan Circle (2021, 51%), advocacy services towards European institutions
Cargo Start (2022, 51%), strengthening Circle’s presence in air cargo digitalization through the StarTracking® platform.
eXyond (2022, 92%), adding capabilities in customs, digital trade, and regulatory processes, exyond also acquired 54.5% of Circle Garage and the business units owned by Telepass Innova SpA (InfoBlu & KMaster) in 2024 and formed a new leading player in the digitisation of logistics
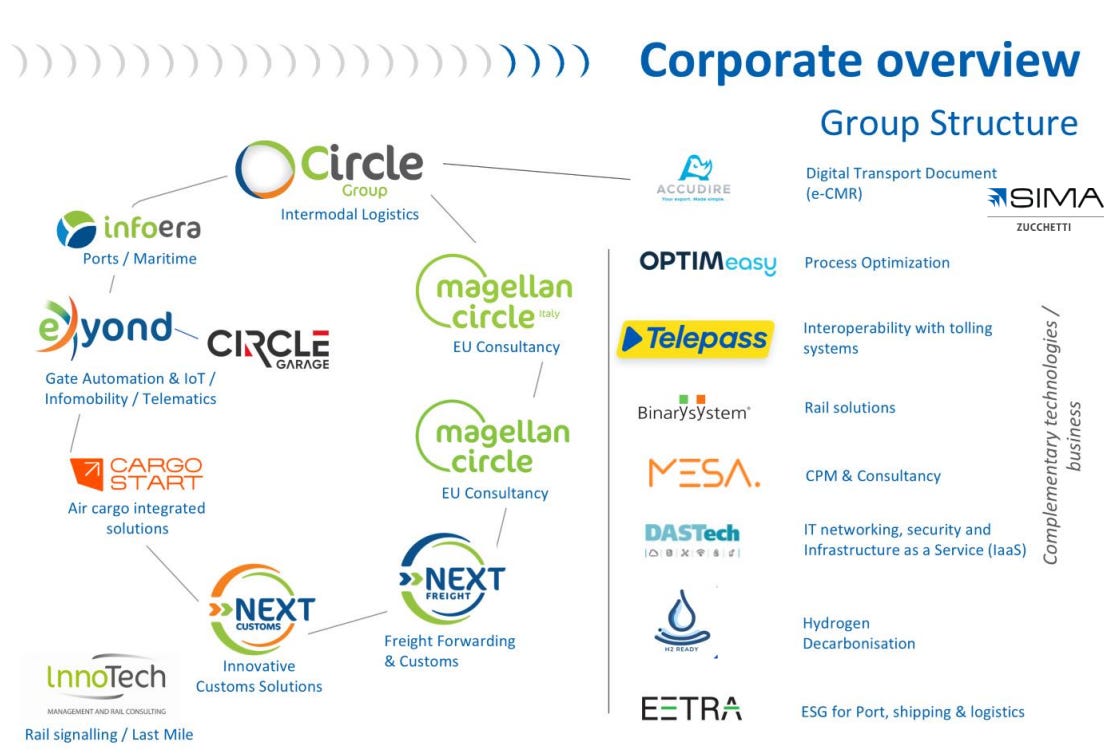
Through these steps, Circle gradually transformed from a port-focused software provider into a multi-platform logistics digitalization group, active across maritime, intermodal, air cargo, and supply-chain visibility.
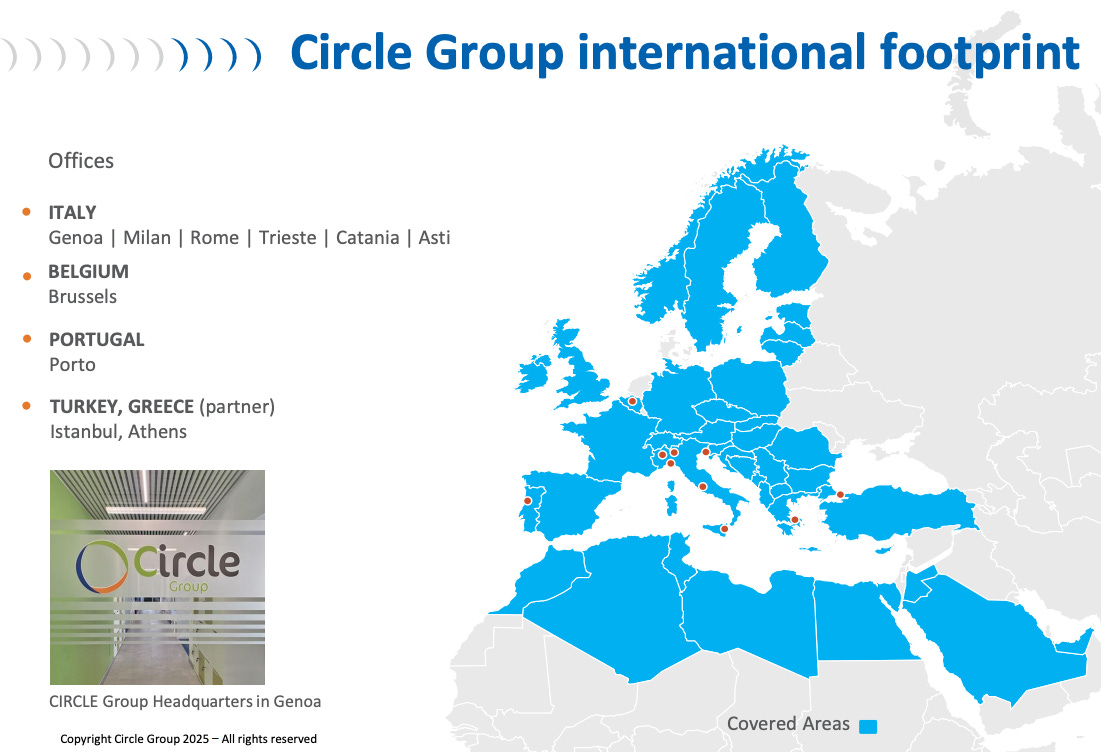
Circle has become an international company with multiple offices in Italy, but also in Belgium, Portugal and partners in Turkey and Greece.
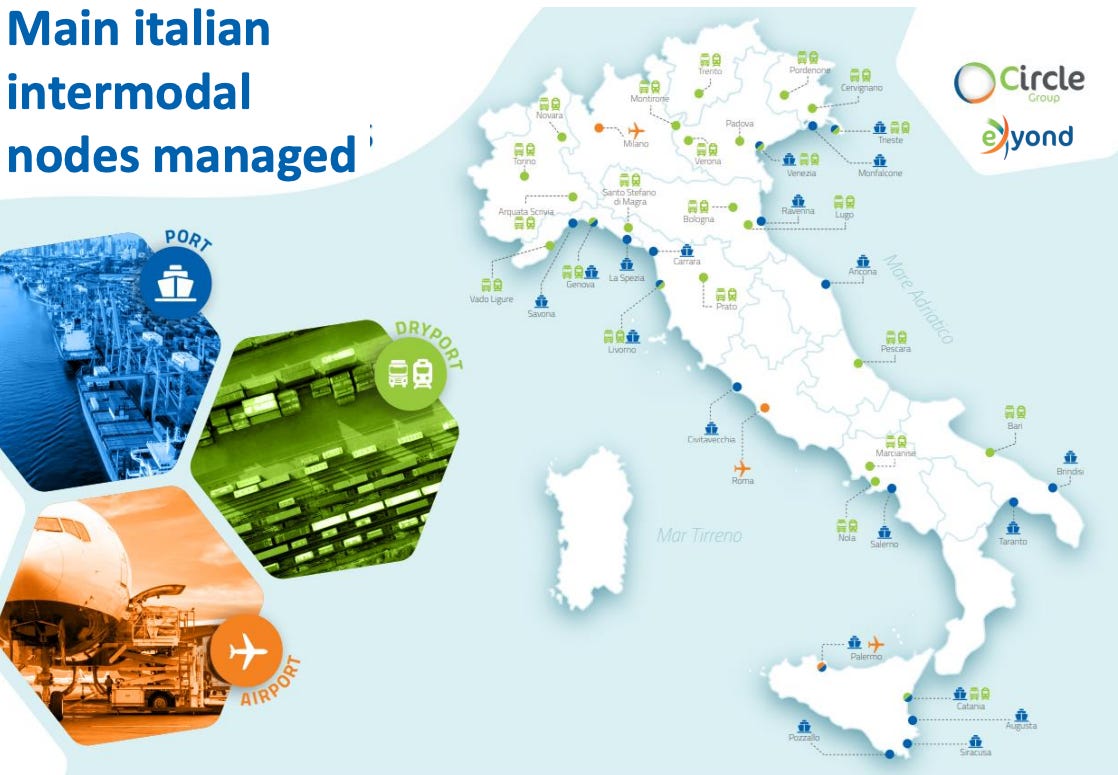
This comprehensive offering has won over many major customers, among others:
PSA Genova Prà: One of the most important terminal operators in the Mediterranean region.
Terminal San Giorgio (Genoa): Uses the Group’s MILOS® Terminal Operating System.
Ports of Trieste, Catania and Livorno: Use of software systems (e.g. Sinfomar® or MILOS®) to digitise port operations.
European Commission: Through Magellan Circle, the group is directly involved in EU projects for the transport sector.
IKEA, Milan Airports, metrocargo, ItalianSped and many more
3. Products & Solutions
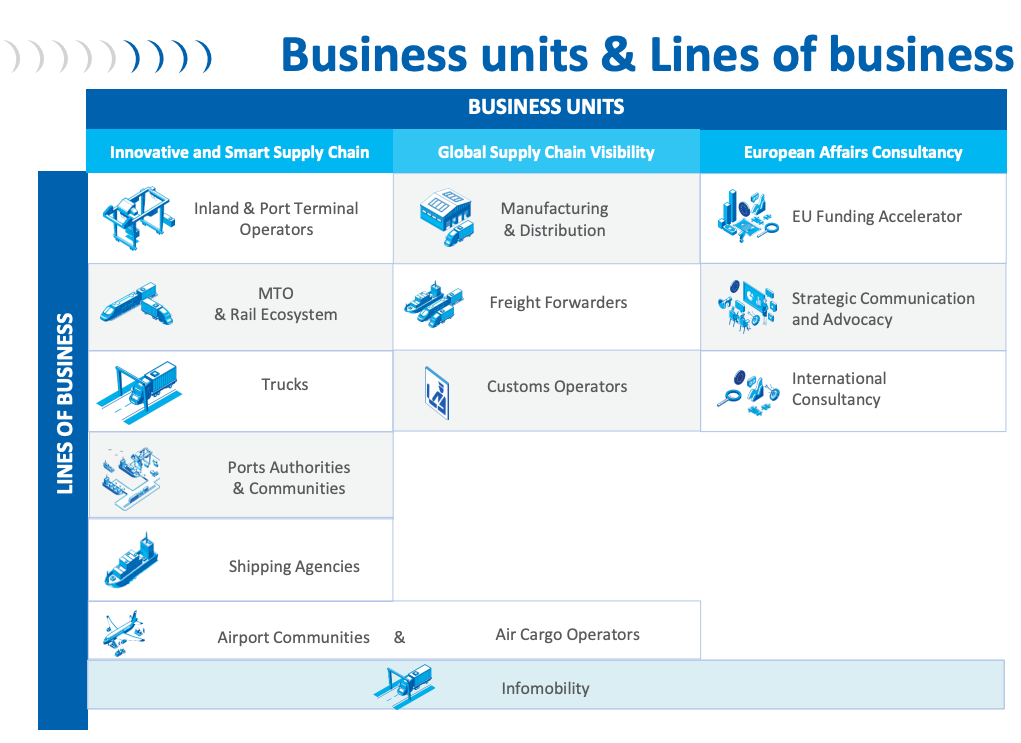
Circle Group organizes its activities around three strategic areas. Together, these areas cover the digitalization of logistics processes, end-to-end visibility across supply chains, and advisory services related to European transport and trade policies.
3.1 Innovative and Smart Supply Chain
This area includes Circle’s core software platforms used to digitalize and optimize logistics operations, particularly in ports, intermodal hubs, and freight networks. The focus is on operational efficiency, coordination between stakeholders, and data-driven decision-making.
Milos Suite
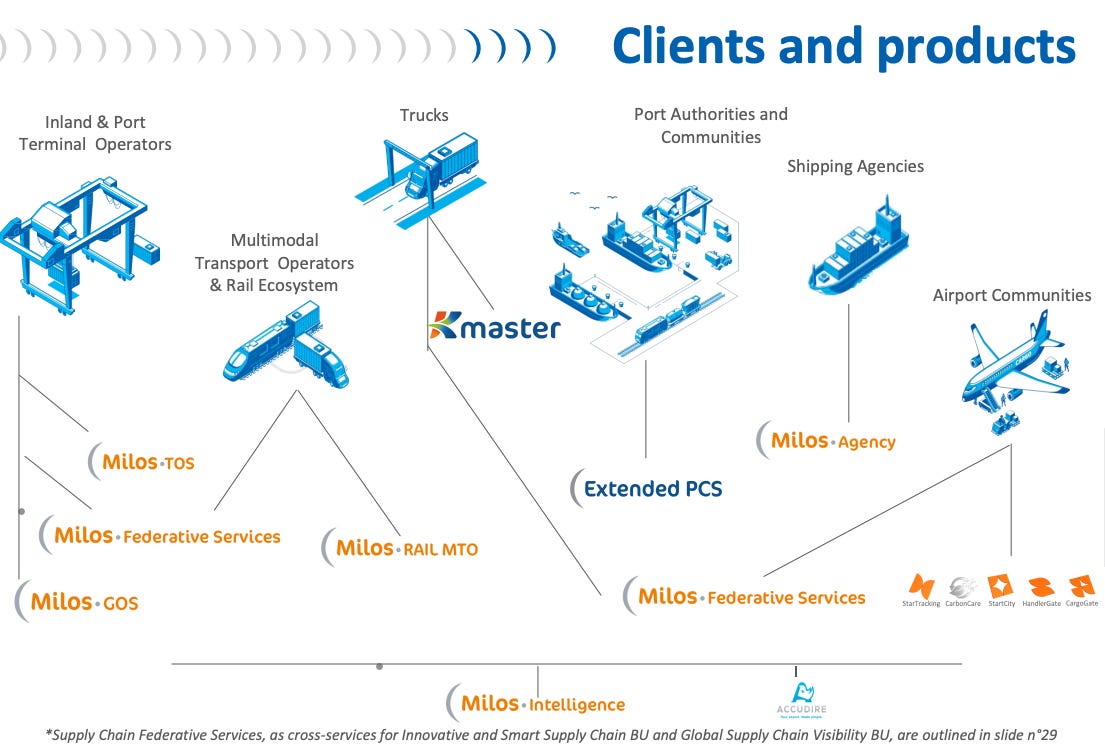
Milos® (Making Intermodal Logistics Optimization Simple) is Circle’s flagship software platform and the technological backbone of the group. It supports ports, terminals, inland hubs, and intermodal operators in managing complex logistics processes.
Key functionalities include:
planning and coordination of cargo flows
operational tracking and status management
data exchange between multiple private and public stakeholders
optimization of terminal and hub operations
Milos® is modular and highly customizable, allowing customers to adopt specific components depending on their operational needs. Available modules are for example:
Milos TOS: Effective global management of a multipurpose terminal, through full, digital streamlined processes and reliable federated interoperability with all the relevant stakeholder’s information systems.
Milos MTO: Managing new rail connections, customer bookings, planning and execution of rail and intermodal transport as well as the full invoicing cycle.
Milos Agency: Software solution tailored specifically for the needs of shipping agents, designed to support them in handling community customs procedures for import and export operations
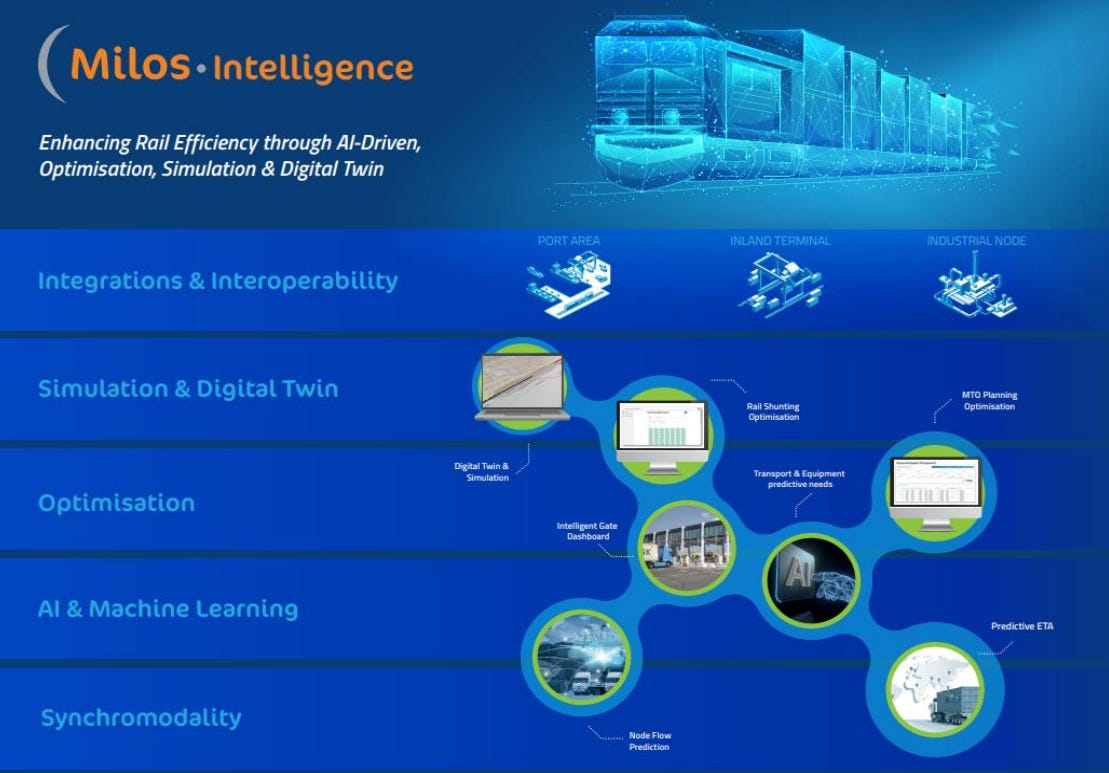
Milos Intelligence: Solutions designed to enhance the planning, optimization, and control of the Supply Chain by integrating ptimization and Artificial Intelligence. It streamlines first and last mile trips, aids in identifying optimal road carriers, optimizes rail operation planning, and enables real-time monitoring and scenario simulation in port areas.
Once implemented, it typically becomes deeply embedded in daily workflows.
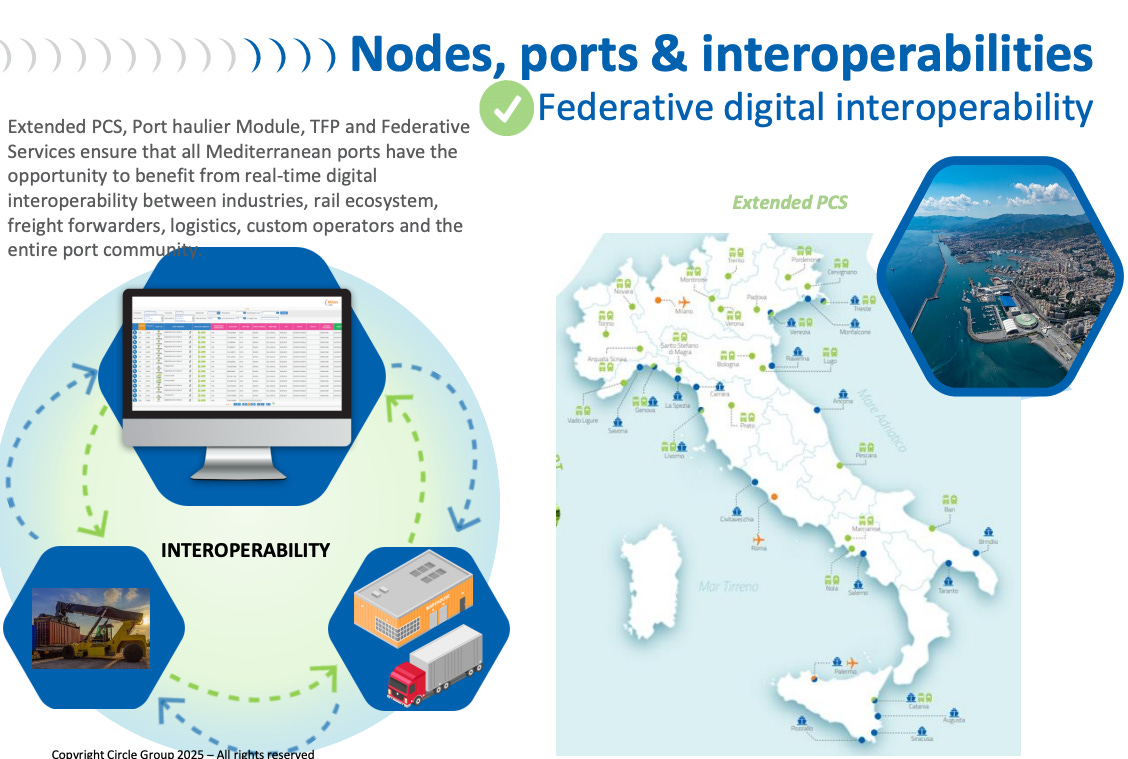
Port Community Systems (PCS)
One stop shop to digitally connect public and private players, effectively implementing port community processes from the Customs Authority to the Coastguard, from shippers to transport providers and MTOs, from last mile logistic operators to shunting companies and from railway undertakings to inland terminals, it allows efficiency and fluidity of traffic to/from ports to be improved and simultaneously represents an important control and monitoring tool.
Star Tracking (Cargo Start)
StarTracking® is a digital air cargo tracking platform developed through the Cargo Start subsidiary.
It enables:
airport-to-airport shipment tracking
real-time status updates
improved data exchange between air cargo stakeholders
StarTracking® extends Circle’s smart supply-chain capabilities into the air cargo segment.
3.2 Global Supply Chain Visibility
This area addresses the growing demand for transparency, resilience, and risk management across international supply chains, particularly for industrial companies and shippers.
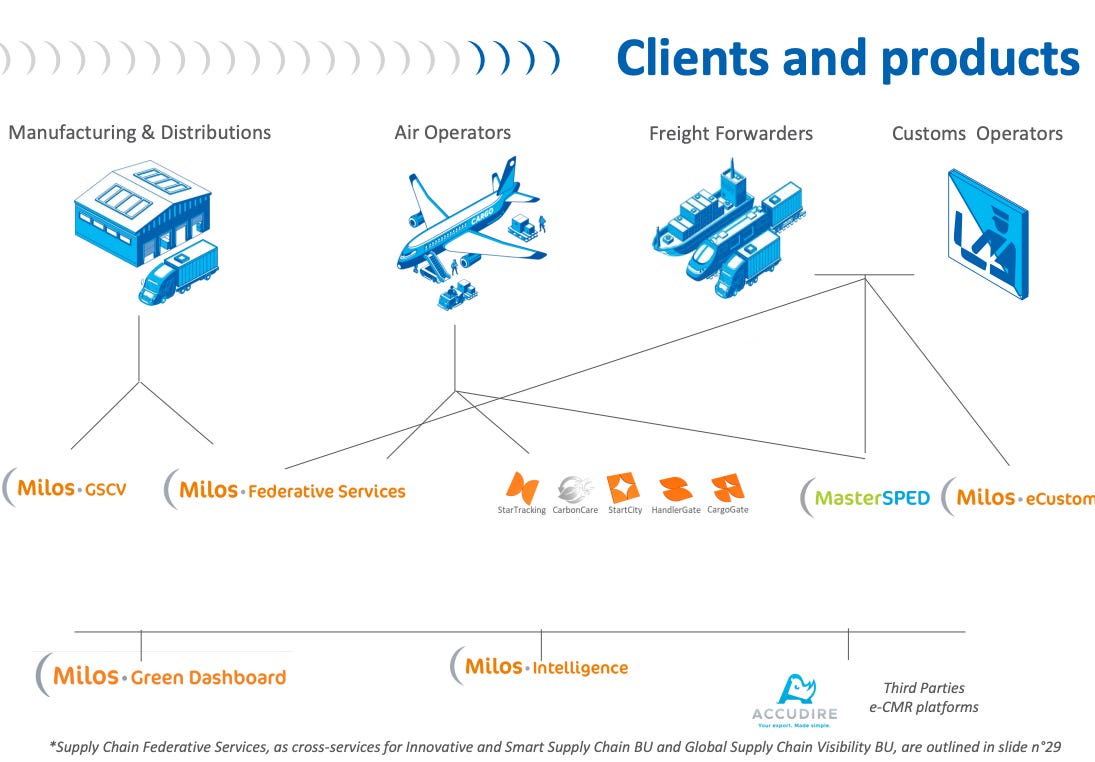
Milos® Global Supply Chain Visibility (GSCV)
Milos® GSCV provides end-to-end visibility across complex, multi-modal supply chains.
The platform offers:
real-time tracking of shipments across transport modes
consolidation of logistics data into a single interface
monitoring of disruptions and delays
GSCV is designed to support decision-making in environments where supply-chain transparency has become strategically and operationally critical.
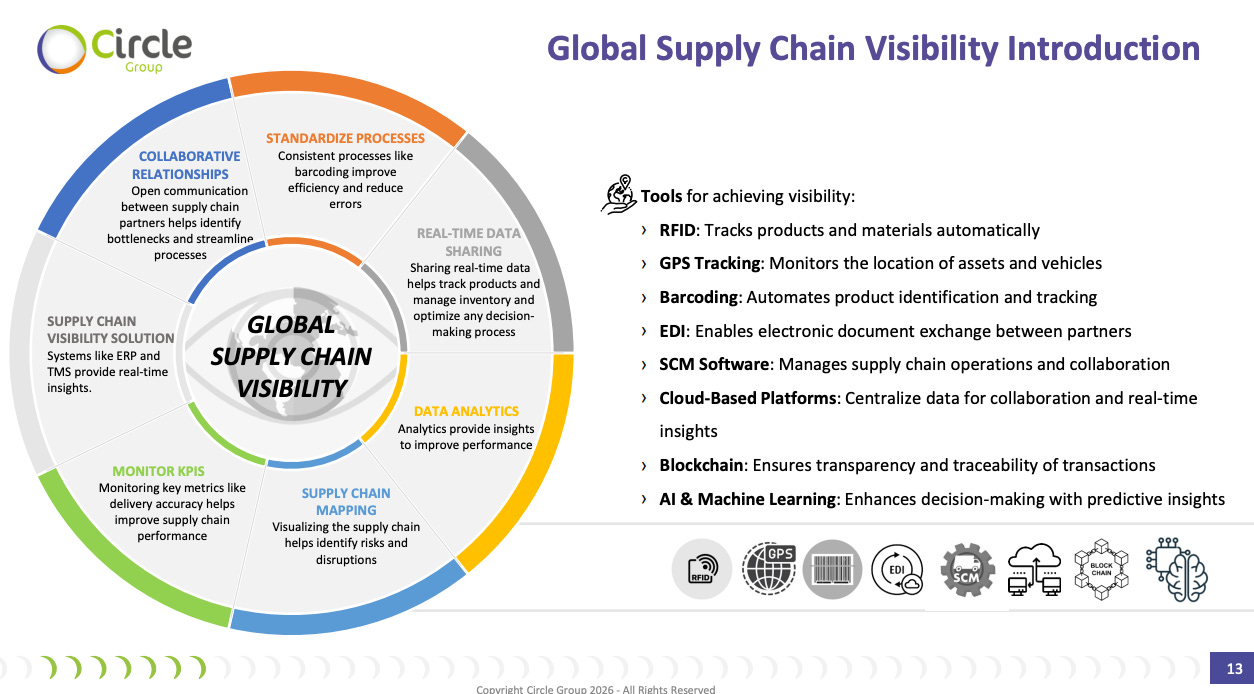
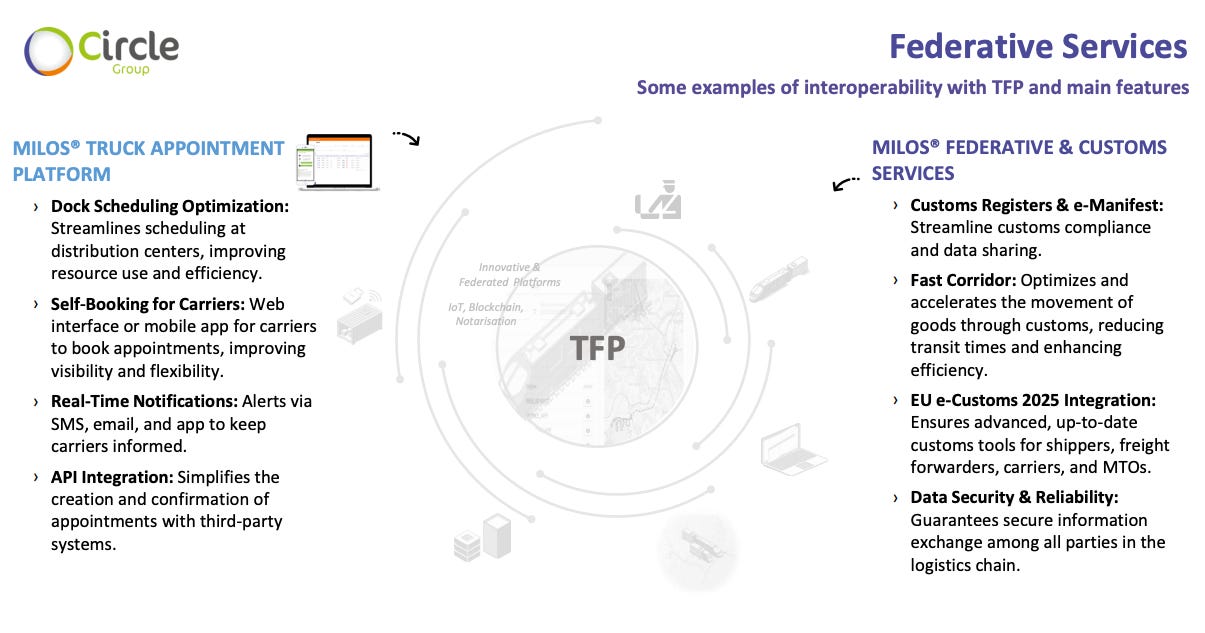
Milos Federative and Customs Services
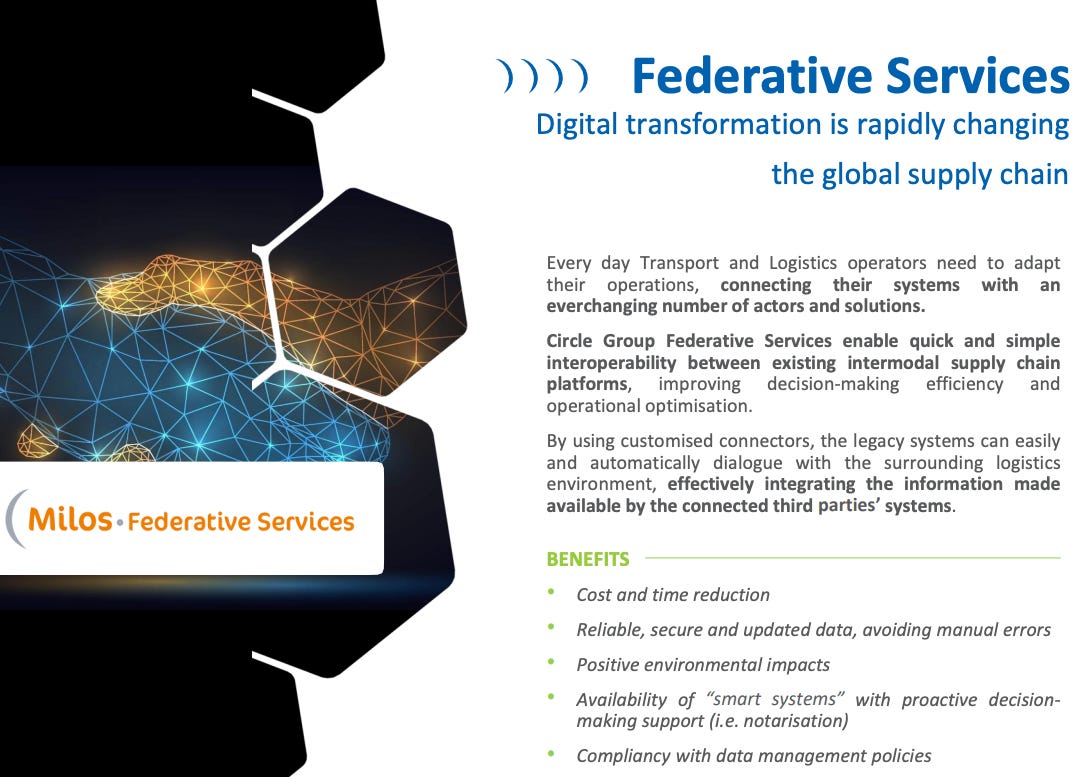
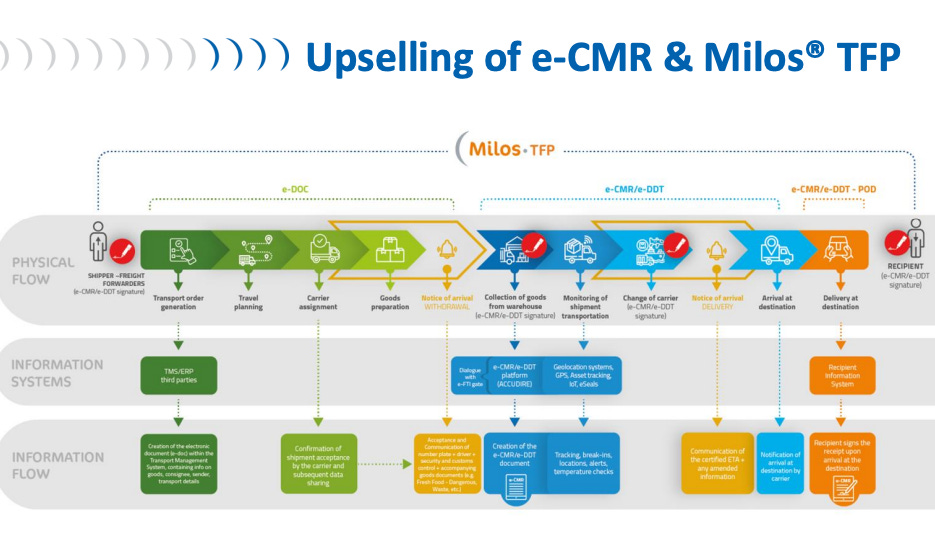
Milos® Federative Services & Customs Services (e-Customs, e-CMR, Controlled Corridors) is a set of tools and services that make it possible to share customs, documentary and transport information between the parties involved in the import/export process, guaranteeing greater data security and reliability. Integration with the latest services provided by national customs (in line with the national plan) and with the systems of national and international authorities (in line with European and national standards) makes the most advanced tools available to shippers, carriers and MTOs.
Overall control of digitally exchanged data and information
Improvement of the logistics process in terms of service quality
Improvement of the logistics process in terms of security (preventing fraud and manual errors)
Reduction of security and operational costs
Reduction in transit and dwell time
Positive environmental impact
MasterSPED® (Next Freight)
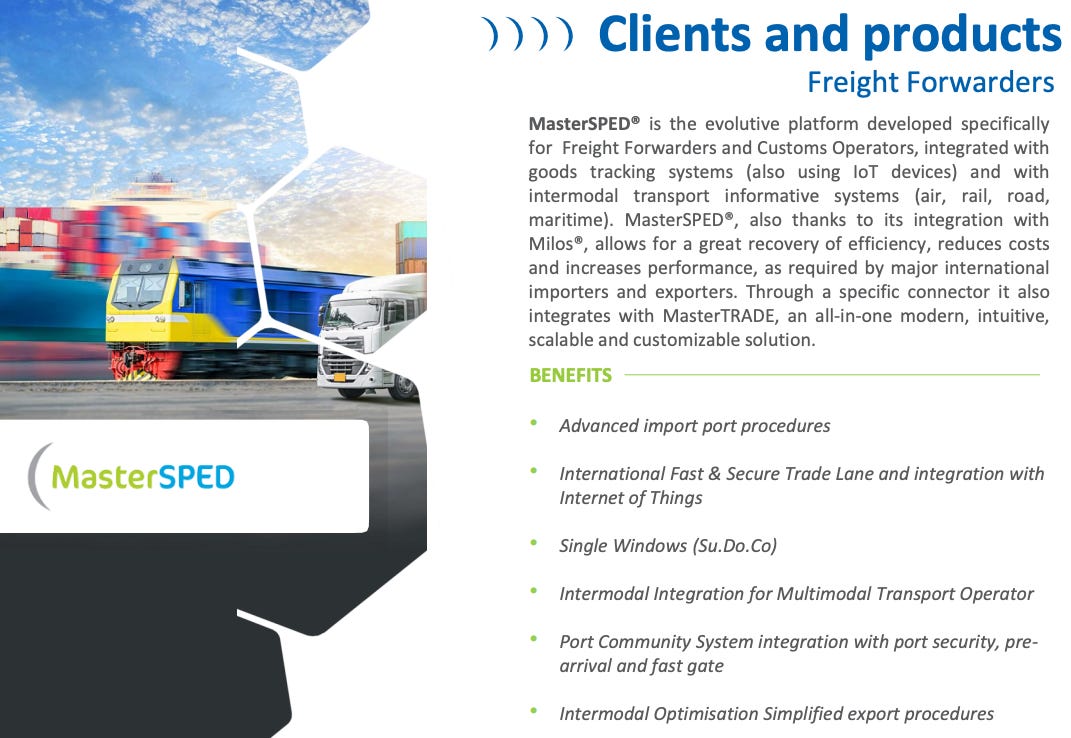
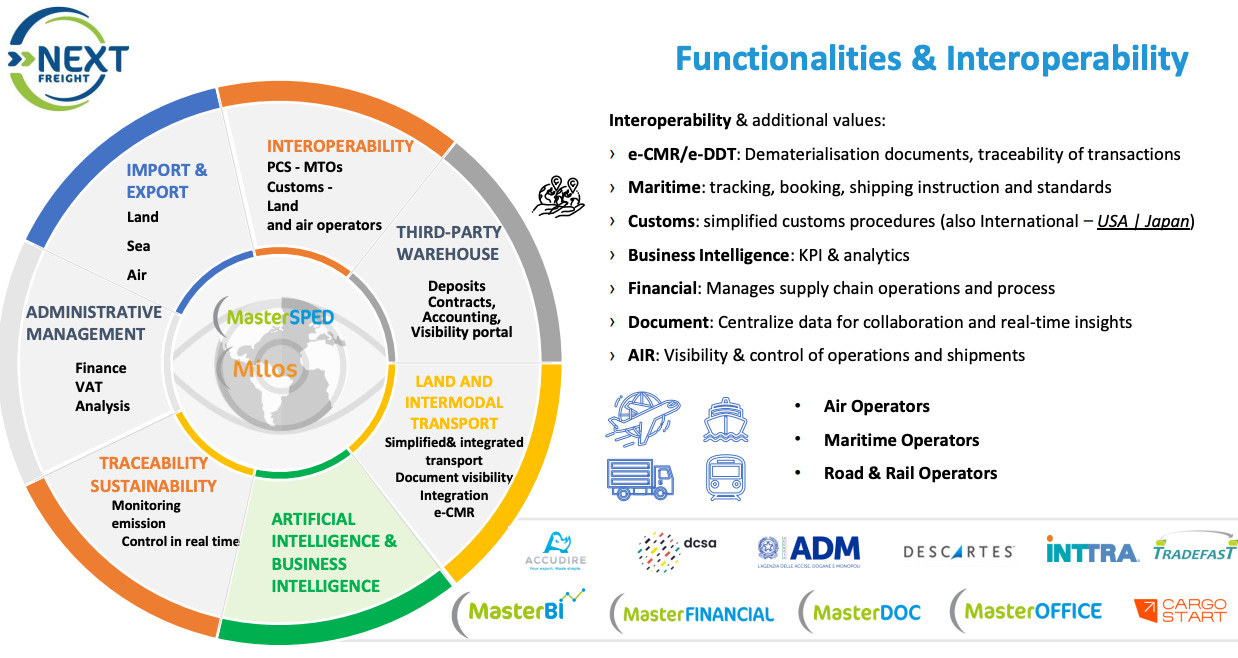
MasterSPED® is an ERP-style solution designed for freight forwarders and customs operators, integrated with goods tracking systems (also using IoT devices) and with intermodal transport informative systems (air, rail, road, maritime).
It supports:
operational management of forwarding activities
documentation and customs-related workflows
integration with regulatory systems and authorities
As customs procedures across Europe become increasingly digitalized, tools like MasterSPED® move from optional efficiency upgrades to operational necessities.
3.3 European Affairs Consultancy
Magellan Circle
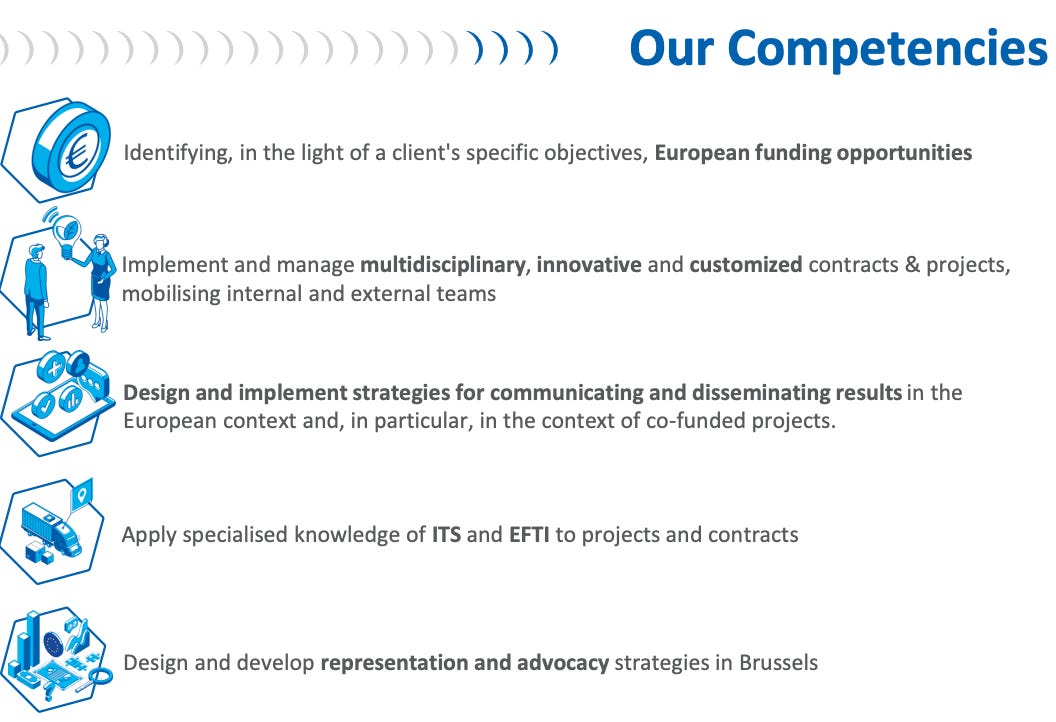
Circle’s third strategic area focuses on consulting and advisory services related to European transport, logistics, and trade policy. This activity complements the software business by aligning technology development with regulatory frameworks.
Circle supports companies and institutions in:
navigating EU transport and logistics regulation
participating in European research and innovation projects
aligning digital solutions with policy initiatives such as the EU Green Deal
This advisory role positions Circle close to policymakers and public institutions, providing early insight into regulatory trends that later translate into software requirements.
If this Under-Followed-Stock sounds interesting to you, you can have a look at my full portfolio with this 1 day free trial for the premium subscription. In addition, you always get the latest information about the companies I own and a review of their earnings.
4. Business Model
Circle Group operates a hybrid business model that combines proprietary software platforms with domain-specific consulting and regulatory advisory services.
This hybrid model creates several competitive advantages:
High switching costs: Once embedded in port or customs workflows, Circle’s software becomes difficult to replace.
Regulatory know-how: Deep understanding of European logistics regulation and public-sector processes.
Niche focus: Ports and intermodal logistics are complex, specialized markets with limited competition from generic software vendors.
Cross-selling potential: Multiple products and subsidiaries allow Circle to expand within existing customer relationships.
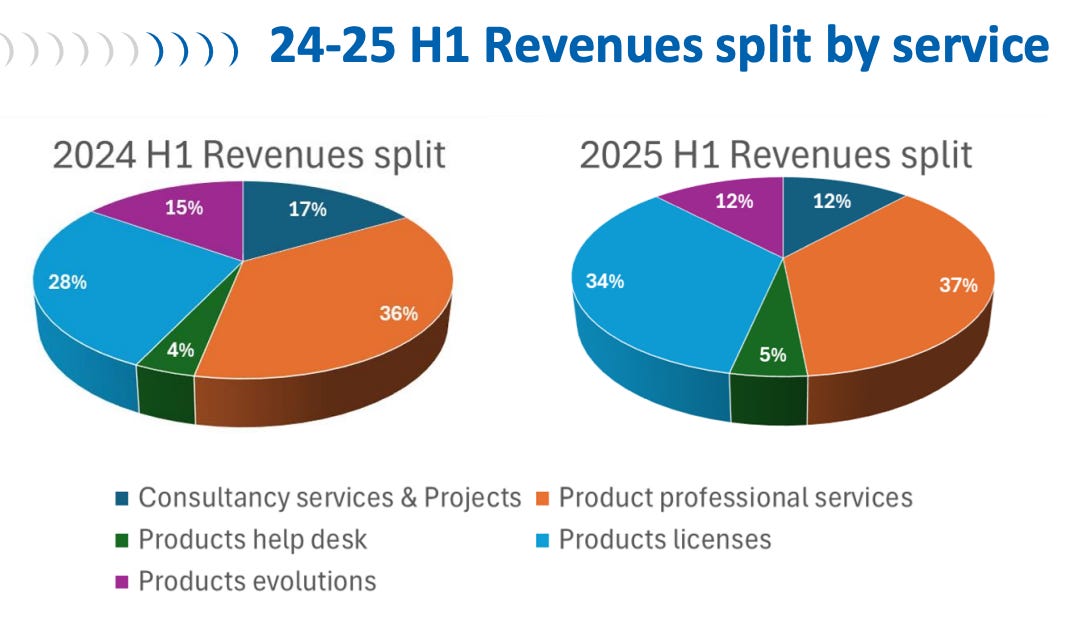
Software Licenses and Recurring Services
A growing share of Circle’s revenues is generated through software licenses and recurring service contracts linked to its proprietary platforms, including Milos®, Port Community Systems, MasterSPED®, and other software solutions.
At the beginning, Circle generated revenues from these software solutions only in a license model, but in 2016, they started to also offer the solutions in more recurring models, where they get a one-time fee for the implementation (MAN/ Man-hours) and then receive recurring revenues via a Software-as-a-Service (SaaS) or Pay-per-use (PPU) model. Over time, the share of the recurring revenues for the proprietary software products became dominant, but licence revenues are also still growing and a big part of the revenues.
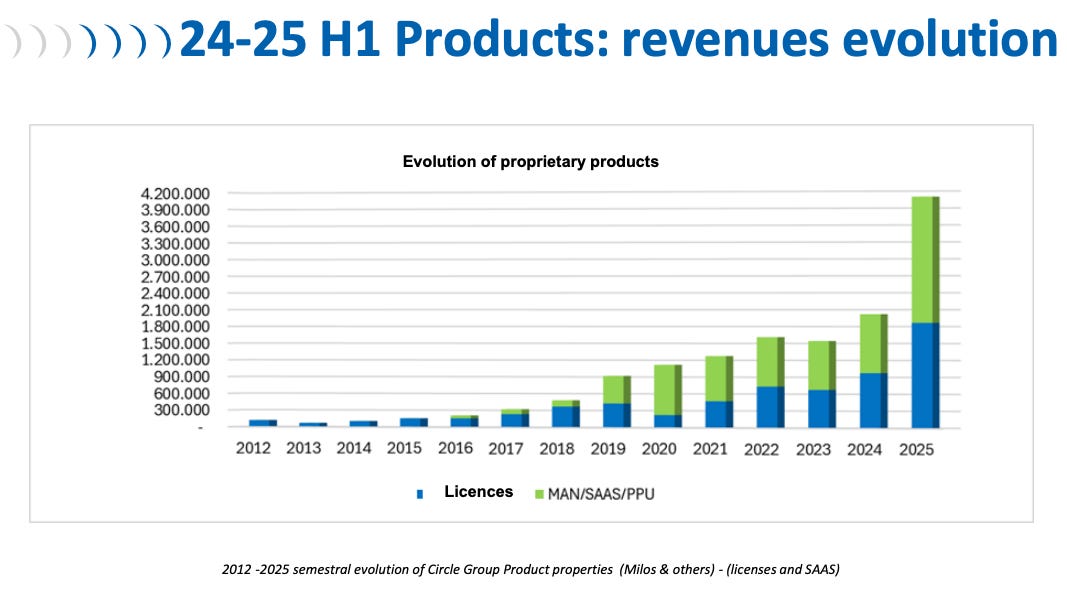
Once deployed, Circle’s software becomes deeply embedded in customer operations, particularly in ports, customs, and regulated logistics environments. As a result, contracts tend to be long-term, renewals are common, and price sensitivity is lower than in discretionary IT spending.
These solutions (Proprietary Software Products & Milos Federative Services) accounted for 42% of total revenues in H1 2025 and the share is expected to continue to grow.
Customization, Integration, and Project Revenues
In addition to standard software offerings, Circle generates revenues from customization, system integration, and project-based implementations.
These activities include:
adapting software platforms to customer-specific workflows
integrating Circle’s systems with third-party and public-sector IT infrastructure
implementing large-scale digitalization projects in ports or logistics hubs
Project revenues are typically non-recurring but serve an important strategic purpose. They allow Circle to:
embed its software deeply into customer operations
establish long-term relationships
create follow-on opportunities for recurring services and upgrades
This model reflects the reality of logistics digitalization, where standardized off-the-shelf software is often insufficient due to regulatory and operational complexity.
Consulting and European Affairs Advisory
Circle also generates revenues from consulting and advisory services, particularly in the area of European transport, logistics, and trade policy.
This includes:
advisory work related to EU-funded research and innovation projects
regulatory consulting for logistics operators and institutions
participation in European initiatives related to digitalization and sustainability
While consulting revenues are generally lower-margin and more project-based, they play a strategic role in Circle’s ecosystem. They provide early insight into regulatory developments and allow the company to shape digital standards that later translate into software demand.
5. Market & Competition
Market Overview
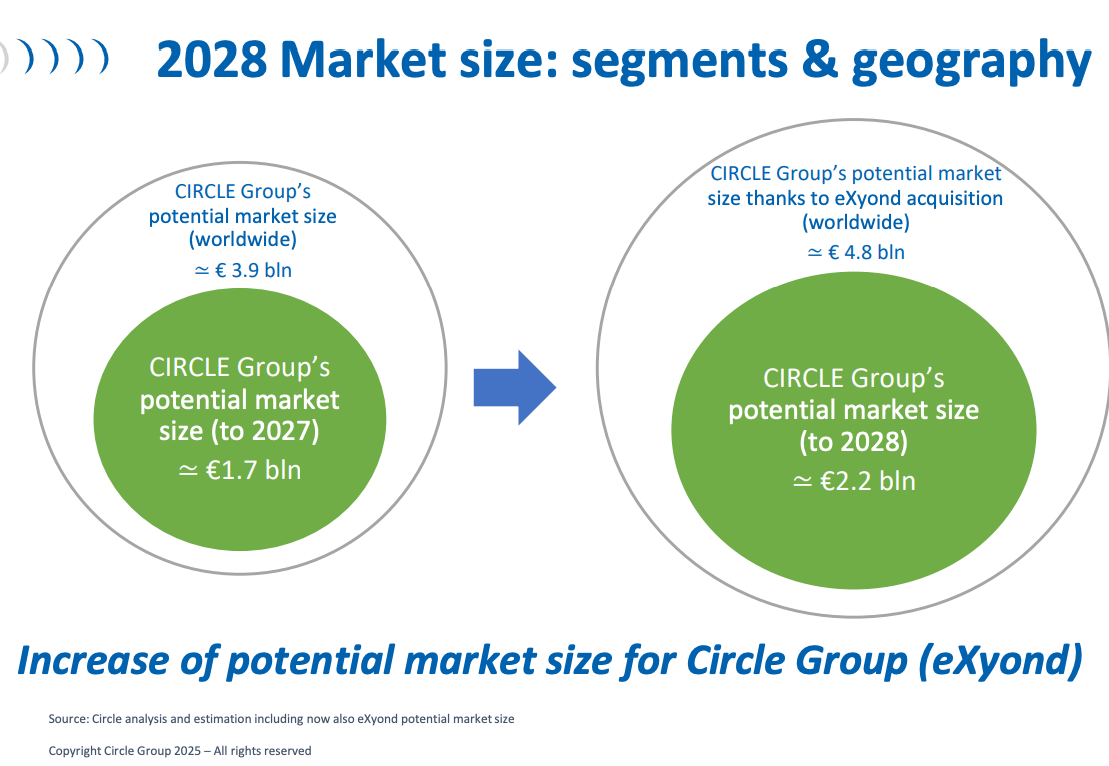
Circle operates in the broader market for logistics, port, and supply-chain digitalization, a segment that is structurally important but historically underinvested in terms of IT and software. Large parts of European logistics infrastructure — particularly ports, intermodal hubs, and customs processes — are still characterized by fragmented systems, manual workflows, and heavy regulatory complexity. This has created a market where digitalization progresses gradually, often driven by regulation and public initiatives rather than purely by cost optimization.
Looking ahead, the long-term outlook for this market is shaped by several structural forces. Regulatory pressure from the European Union is increasing, particularly around digital documentation, customs harmonization, sustainability reporting, and emissions transparency. At the same time, supply-chain disruptions over recent years have highlighted the need for better visibility, resilience, and coordination across transport nodes. These trends are unlikely to reverse and support sustained demand for software platforms that can handle compliance, data integration, and operational coordination in complex environments.
From a market-size perspective, logistics IT and supply-chain software represent a multi-billion-euro market in Europe, growing at mid-single-digit rates overall. Within this, niche segments such as port community systems, customs digitalization, and intermodal coordination tend to grow slightly faster, supported by regulation rather than purely by discretionary IT spending. Growth is uneven and often linked to (lengthy & slow) public-sector investment cycles, EU funding programs, and regulatory deadlines.
Competitive Landscape
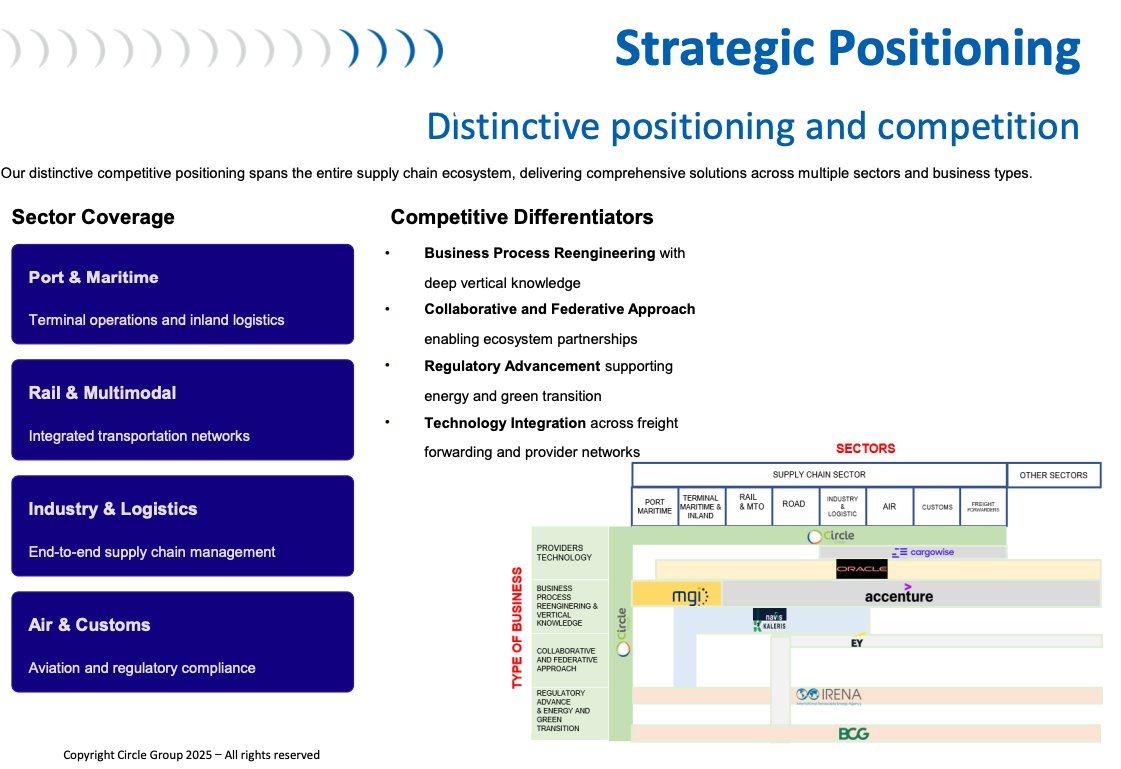
Competition in Circle’s markets is fragmented and can be broadly divided into three groups:
Large global software vendors and system integrators
Players such as SAP, Oracle, or large IT integrators offer broad ERP and logistics solutions. While powerful, these systems often lack deep specialization in ports, intermodal transport, and European regulatory workflows, leading to customization-heavy and costly implementations.
Specialized niche software providers
Numerous smaller companies, like cargowise focus on individual modules such as terminal operating systems, customs software, or tracking tools. These players often excel in narrow use cases but lack the breadth or integration capabilities to support complex, multi-stakeholder environments.
Public-sector or semi-public platforms
In some cases, ports or authorities develop or sponsor their own systems. These solutions are often slow to evolve and limited in scalability, creating opportunities for specialized private providers.
Circle positions itself between these extremes: more specialized than large vendors, but broader and more integrated than single-module niche players. Its competitive strength lies less in technology alone and more in regulatory know-how, integration capability, and long-term operational reliability.
6. Growth Drivers & Catalysts
6.1 Regulatory-driven digitalization
One of the most important long-term growth drivers for Circle is the continued digitalization of logistics and trade processes mandated or encouraged by European regulation. Initiatives such as electronic customs procedures, digital transport documents, and harmonized data standards gradually increase demand for software platforms capable of handling compliance and data exchange across borders.
Circle’s close involvement in European affairs and regulatory initiatives allows it to anticipate these developments and align its product roadmap accordingly. This creates a structural tailwind that is largely independent of short-term economic cycles.
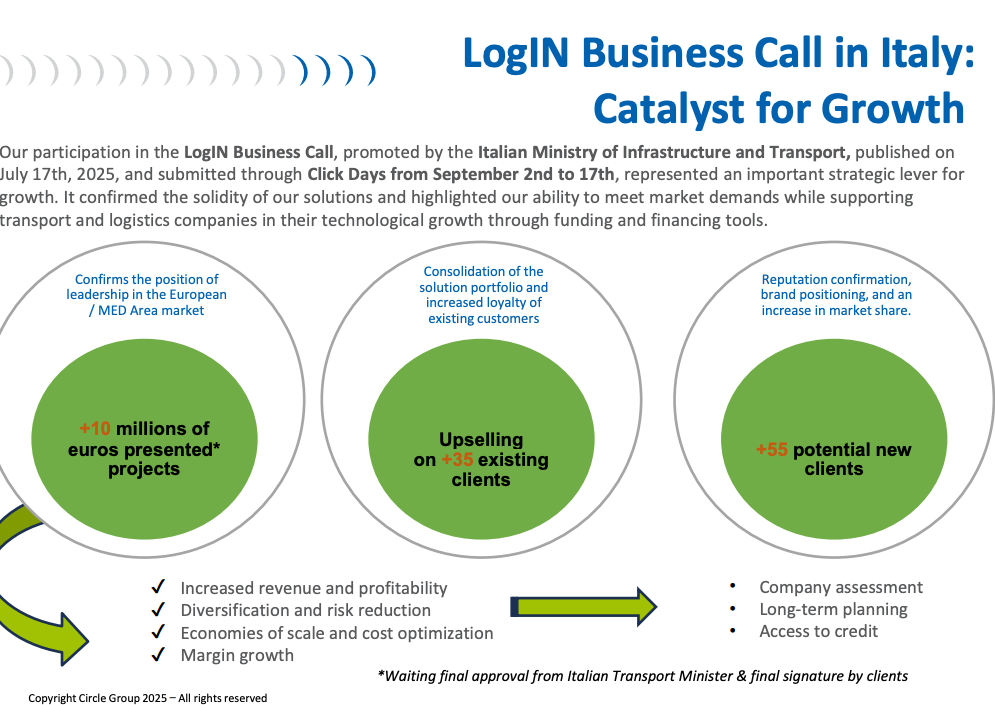
A key example is the EU eFTI Regulation (Electronic Freight Transport Information), which requires member states to accept electronic transport documents across all transport nodes by 2027. Magellan Circle (Circle’s European Affairs Consultancy) was part of the EU-funded eFTI4LIVE project to develop frameworks and the organization of the European stakeholders. Afterwards, the Circle subsidiary Next Freight entered into a contract to develop and pilot the eFTI platform. Being so closely involved in the development of regulations and their technical implementation naturally helps Circle to integrate this perfectly into its own suite of software solutions. Thanks to its interoperability with Circle’s Milos® Transport Federative Platform, the eFTI Platform enables the exchange of data with authorities in compliance with the eFTI Regulation, guaranteeing digital B2A (Business to Administration) interaction with control authorities.
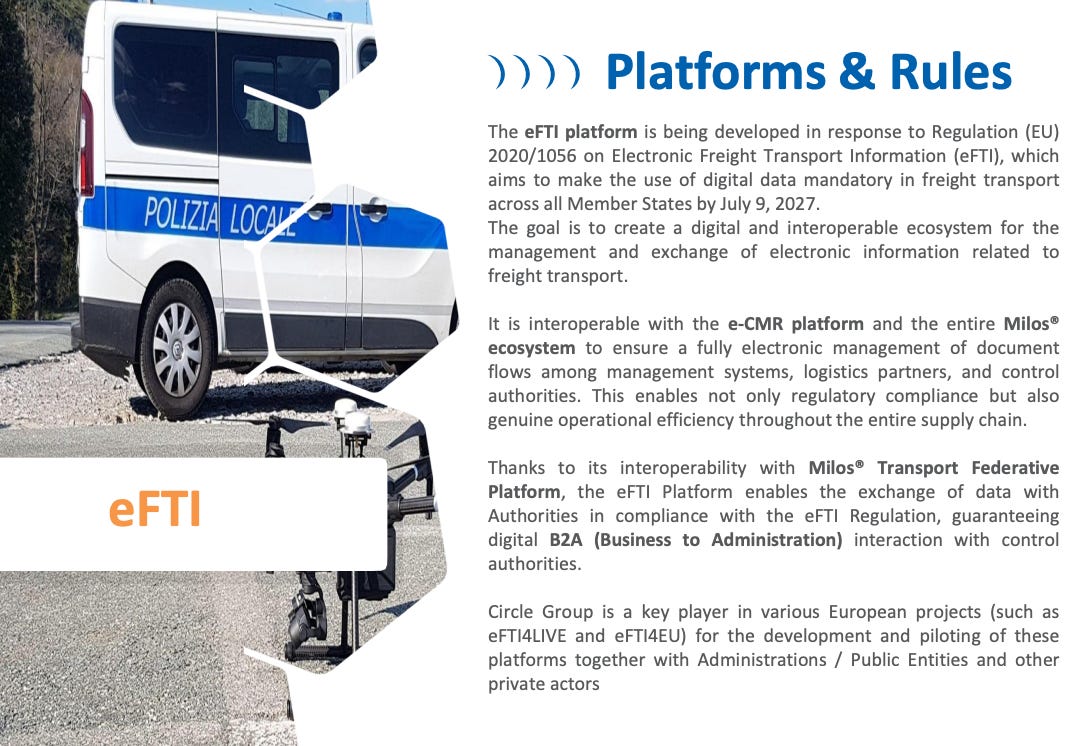
Similarly, initiatives such as LogIN Business Network in Italy aim to standardize and digitalize data exchange across national logistics chains, connecting ports, inland hubs, and operators into a shared digital framework.
For Circle, these initiatives translate into:
increased demand for Port Community Systems
upgrades and extensions of existing Milos® installations
new implementation projects triggered by compliance requirements
6.2 Increasing complexity of logistics networks / Need for end-to-end supply chain visibility
European supply chains are becoming more complex rather than simpler. Intermodal transport, sustainability requirements, and resilience considerations add layers of coordination between ports, inland hubs, freight forwarders, and public authorities.
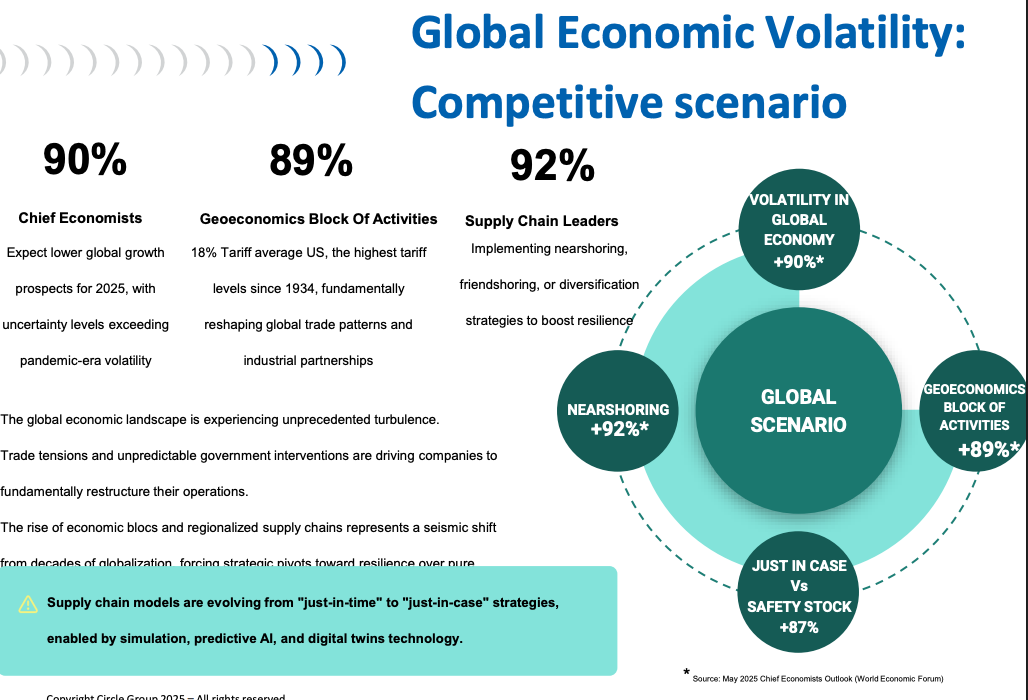
The global economic volatility is increasing due to trade tensions and unpredictable government interventions. Industrial companies and shippers are increasingly demanding real-time visibility across their supply chains to monitor these risks and act accordingly.
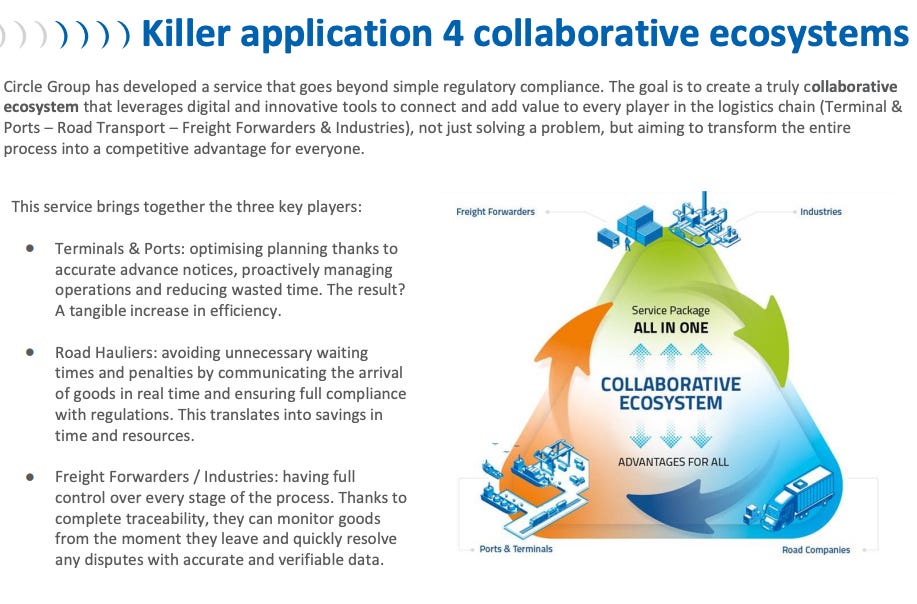
This complexity increases the value of integrated platforms such as Milos®, Port Community Systems, and Next Freight, which are designed to manage multi-stakeholder environments rather than isolated workflows. Circle has developed its MILOS intelligence solutions to bring together all necessary information of the three key logistic players: Terminal & Ports, Road Hauliers and Freight Forwarders / Industries. Covering the entire logistics chain with a dedicated software solution and then being able to analyze & interpret this data to optimize the overall process can be a key advantage for Circle over other isolated solutions.
6.3 Cross- and Upselling / New products
Circle typically enters customer relationships through a specific operational or regulatory use case — for example a Port Community System, a Milos® implementation at a terminal, or a customs-related solution. Once embedded, the company gains deep insight into customer workflows, regulatory constraints, and data flows.
This positioning creates several cross- and upselling opportunities:
Module expansion:
Customers using a limited set of Milos® modules can add planning, tracking, optimization, or analytics components over time as digital maturity increases.
Vertical expansion across the logistics chain:
Port or terminal customers can later adopt intermodal, inland, or air-cargo-related solutions, while freight forwarders can add visibility or customs modules.
Regulatory add-ons:
Customers initially focused on operational efficiency may later require customs, compliance, or sustainability reporting solutions, particularly as regulation evolves.
Usage-based scaling:
Pay-per-use (PPU) models allow revenues to grow naturally with transaction volumes without renegotiating contracts.
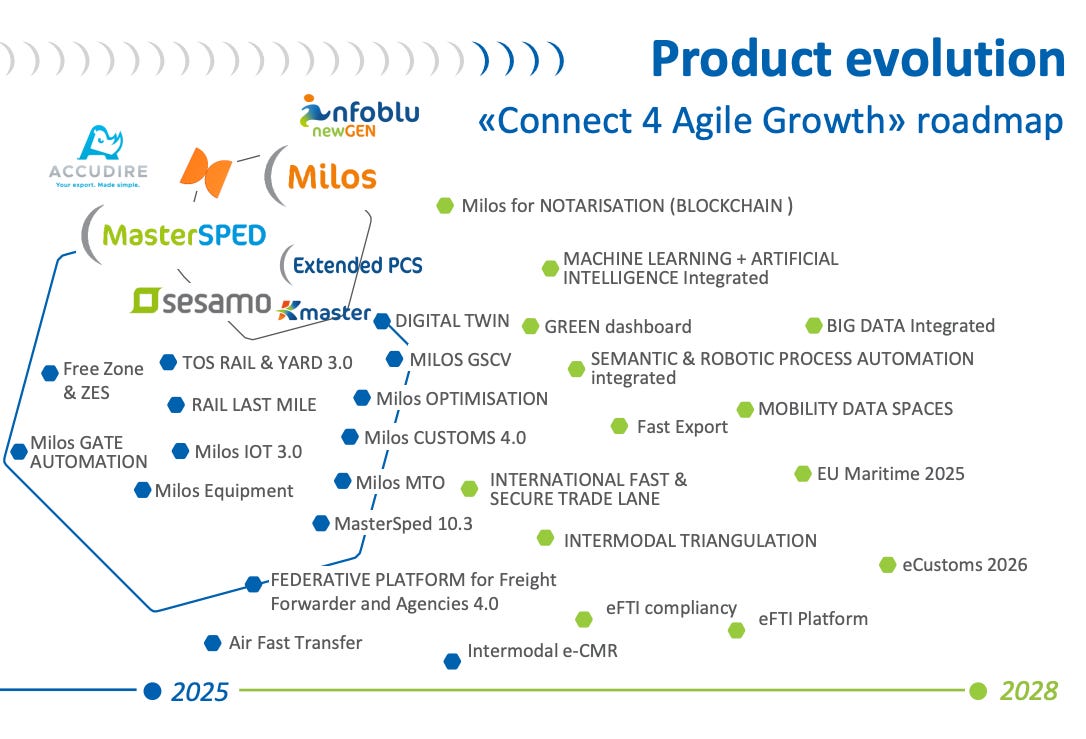
Due to its close cooperation with all players in the supply chain, Circle often quickly recognizes their need for new or complementary products and can develop these based on its own expertise and then offer them to customers.
6.4 Shift to recurring revenues
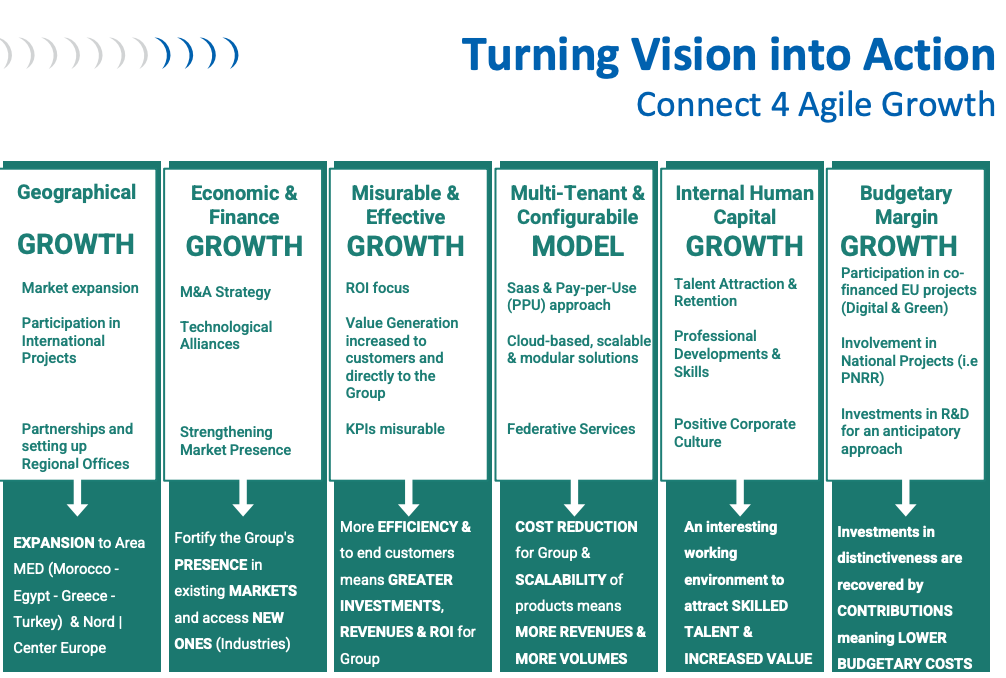
Circle is gradually evolving its revenue mix toward recurring software revenues and usage-based models (SaaS and PPU). In the first half of 2025, the recurring revenues (Proprietary Software & Milos Federative Services) grew significantly faster than the other revenue lines.
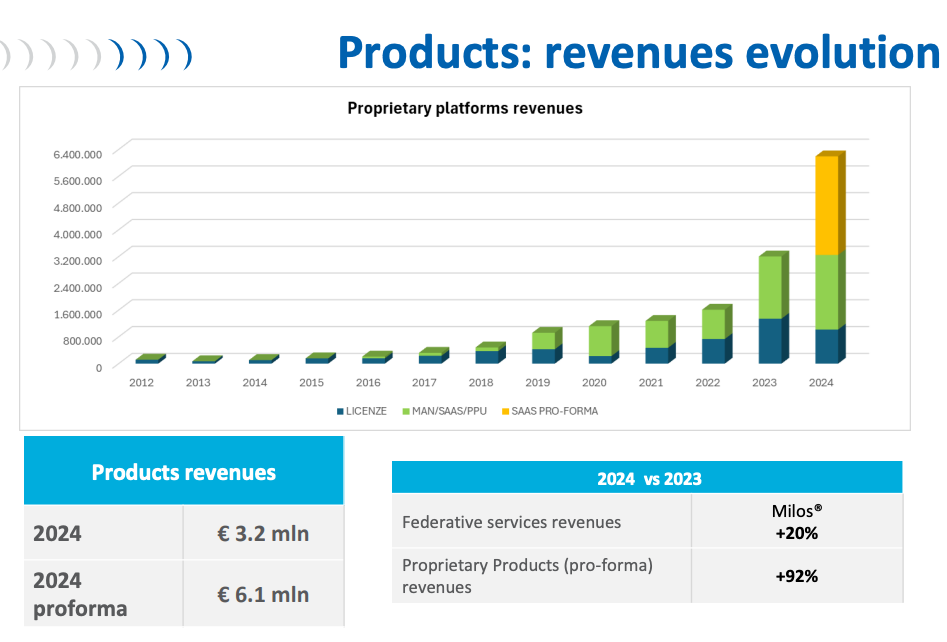
While project and consulting revenues remain relevant, the increasing installed base of software platforms creates opportunities for:
recurring maintenance and service contracts
module upgrades
volume-driven PPU revenues as transaction volumes grow
This shift supports operating leverage and improves the quality of revenues over time as well as the margin profile.
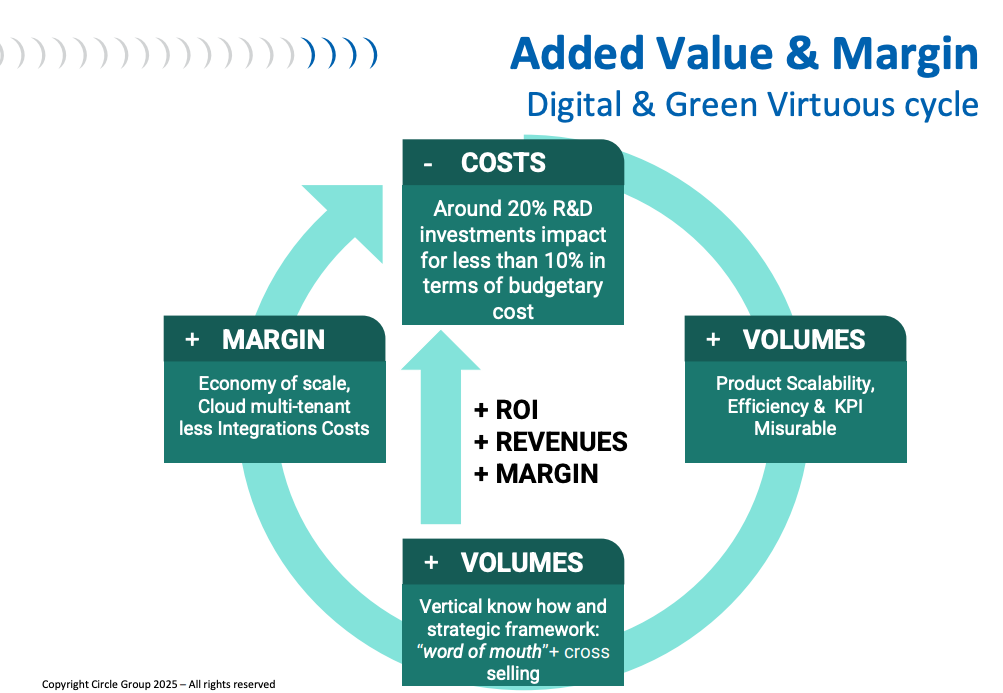
6.5 Geographical Expansion
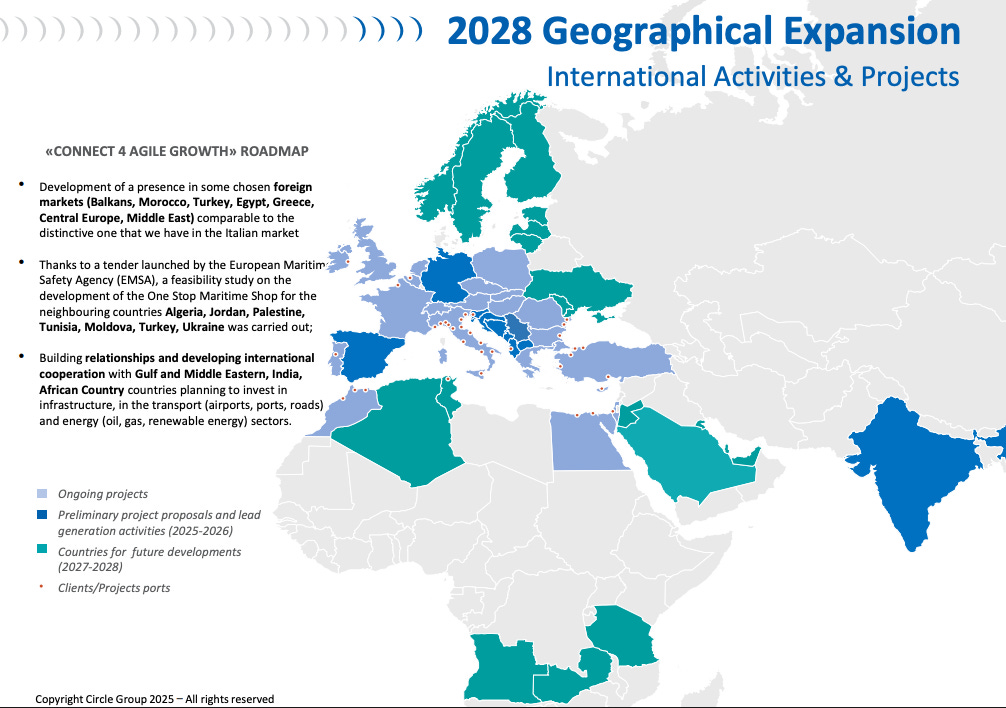
Italy is Circle’s core market, but the company has also worked on projects in multiple countries in and around Europe. In 2024, Circle generated 28% of revenues in markets outside of Italy (vs. 26 % in 2023). In the near-term, Circle aims to develop a presence in some chosen foreign markets like the Balkans, Morocco, Turkey, Egypt, Greece, Central Europe and in the Middle East. Thanks to a tender launched by the European Maritime Safety Agency (EMSA), a feasibility study on the development of the One Stop Maritime Shop for the neighbouring countries Algeria, Jordan, Palestine, Tunisia, Moldova, Turkey and Ukraine was carried out, which can be a good entry point for Circle if it comes to the implementaion. Especially foreign countries where large investments in infrastructure & the transport sector are planned, can present a lucrative target for Circle.
6.6 M&A
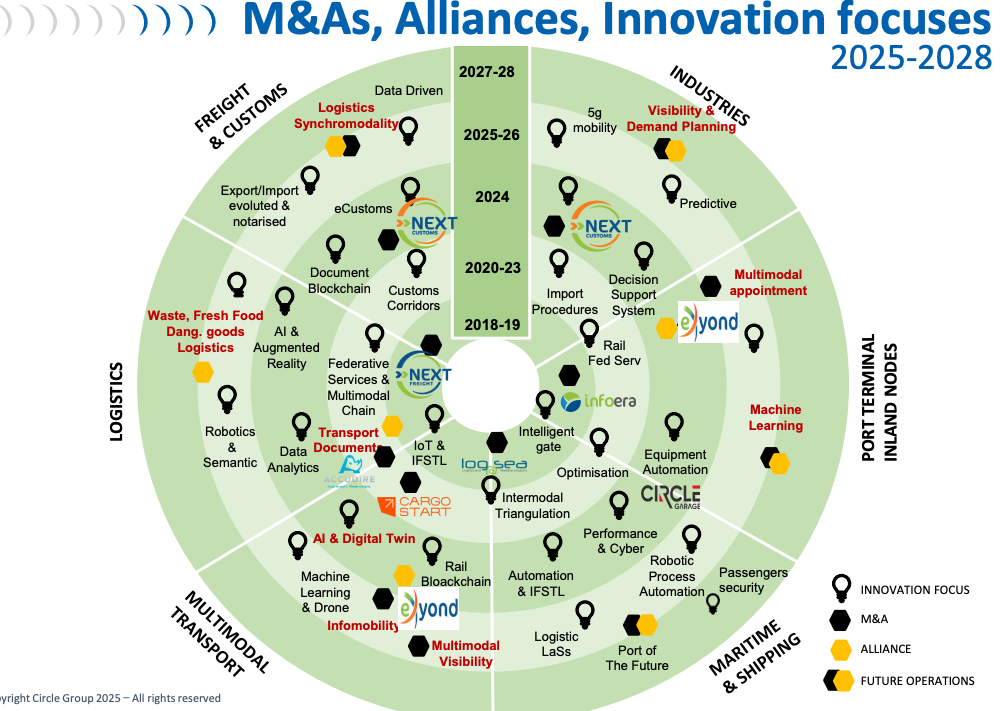
The management has historically used acquisitions to expand Circle’s capabilities into adjacent niches such as air cargo and customs. Future acquisitions are likely to remain selective, aimed at reinforcing existing platforms rather than transforming the group’s strategic direction. So one can expect further bolt-on acquisitions in areas where the management is seeing opportunities to expand its offering.
7. Shareholders & Management
Management
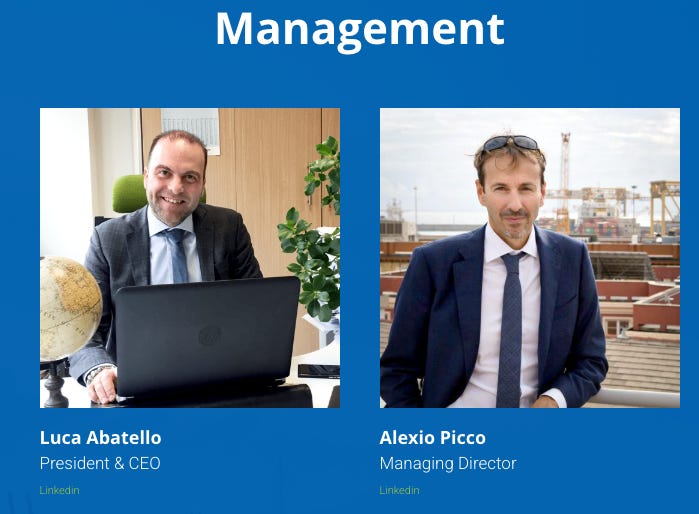
Luca Abatello — Founder & CEO
Luca Abatello is a co-founder of Circle and has served as Chief Executive Officer since inception. He has a degree in Economics and Commerce from the University of Genoa, as well as the Executive MBA from SDA Bocconi in Milan. In addition, he has a background in logistics, software, and digital transformation and has overseen Circle’s evolution from a niche Italian logistics software provider to a multi-platform group focused on ports, intermodal logistics, customs, and supply-chain digitalization.
Alexio Picco — Co-Founder & Director
Alexio Picco is another co-founder and has historically been involved in Circle’s strategic and operational activities, particularly in areas such as internationalization and EU regulatory engagement. He graduated in Transportation Engineering from the University of Genoa in 2004 and has held the position of independent expert for the evaluation of innovative projects at the European Commission since 2007.
Shareholders
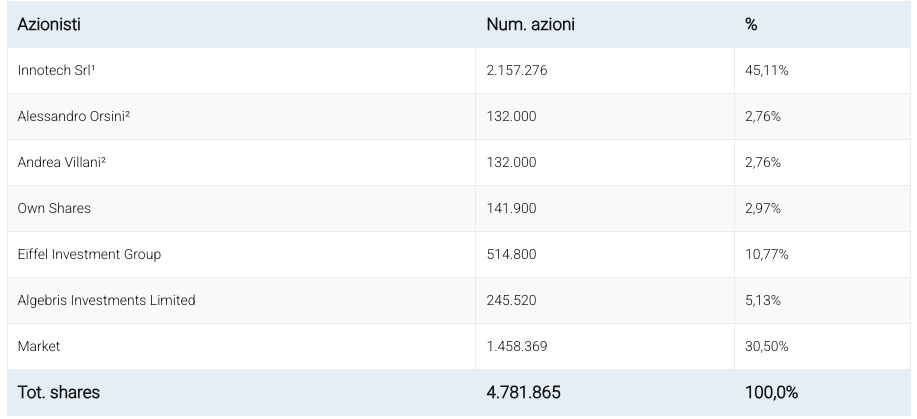
The CEO & Founder, Luca Abatello, still owns 45.11 % of Circle via its investment company, Innotech Srl. Other large investors include the investment companies Eiffel Investment Group (10.77%) and Algebris Investments Limited (5.13%). Eiffel Investment Group became a shareholder in June 2025 via a capital increase reserved for institutional investors of 514,800 newly issued shares for EUR 7 per share. Algebris became a larger shareholder in December 2025 during a capital increase to finance the acquisition of the Telepass business units. Circle issued 165,000 new shares for EUR 7.15 per share.
The free float of Circle is only 30.5 %.
The CEO’s remuneration appears normal and there were no other notable related party transactions.
8. Financials
Since 2012, Circle has been able to continuously increase revenues thanks to organic growth as well as systematic M&A. The Value of Production grew with a CAGR of 25% from 2012 to 2025.
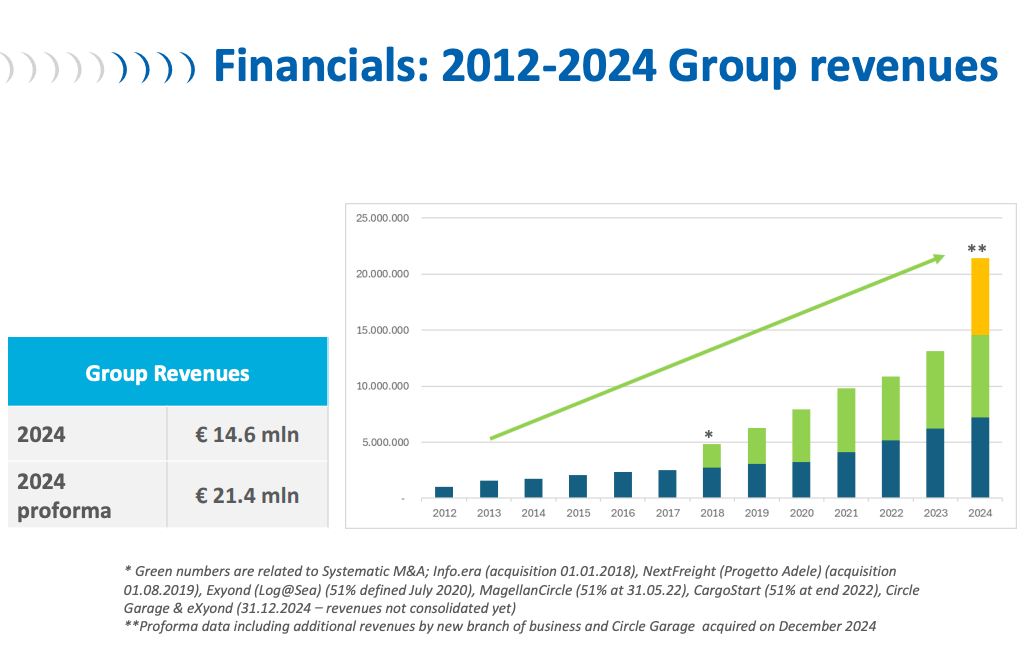
At the end of 2024, Circle acquired via its subsidiary exyond (92% ownership) two Business Units from Telepass (Infomobility & Telematics) for EUR 6.2 million. These two Business Units added EUR 6.5 million in revenues in 2024 (of which EUR 3 million was from proprietary products) and EUR 1.3 million in EBITDA (EV/EBITDA multiple of 4.8x). In addition, exyond acquired 54.54 % of Circle Garage, adding EUR 0.3 million in revenues and EUR 0.1 million in EBITDA. Circle integrated these companies into exyond to form a leading player in the digitisation of logistics, providing advanced solutions to optimise the entire intermodal supply chain.
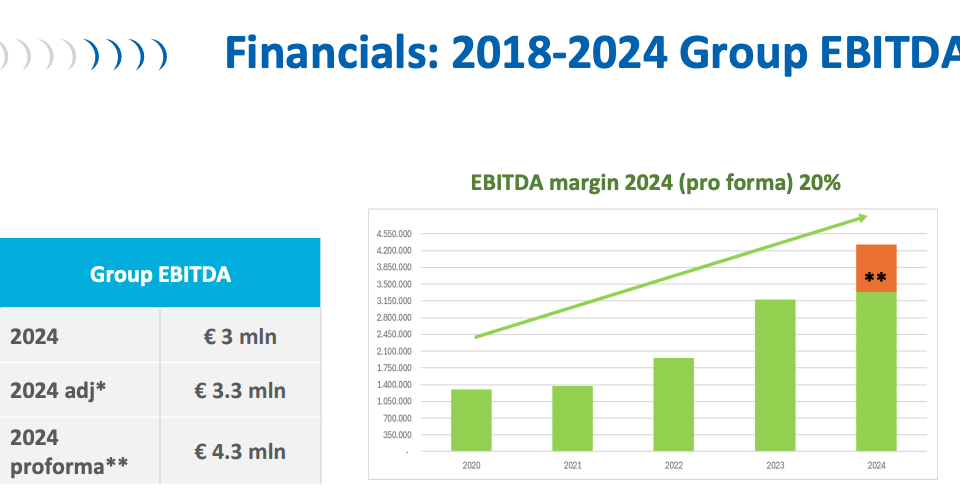
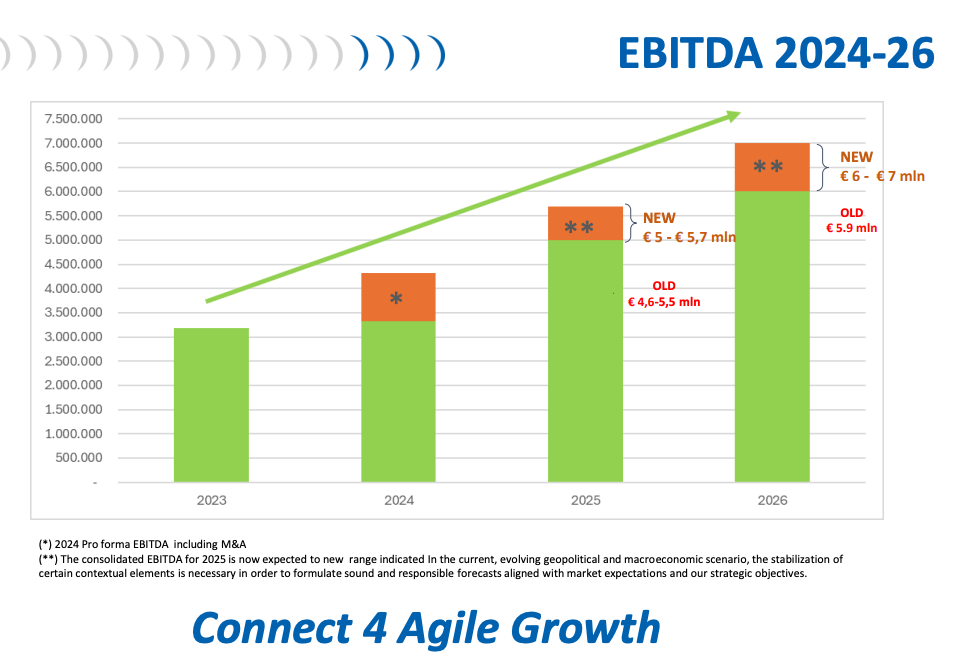
On a pro forma basis (including the acquisitions from December), revenues in 2024 reached EUR 21.4 million and EBITDA EUR 4.3 million. Without consolidation, Circle would have reached revenues of EUR 14.6 million (+10% yoy) and adj. EBITDA of EUR 3.3 million (+5%).
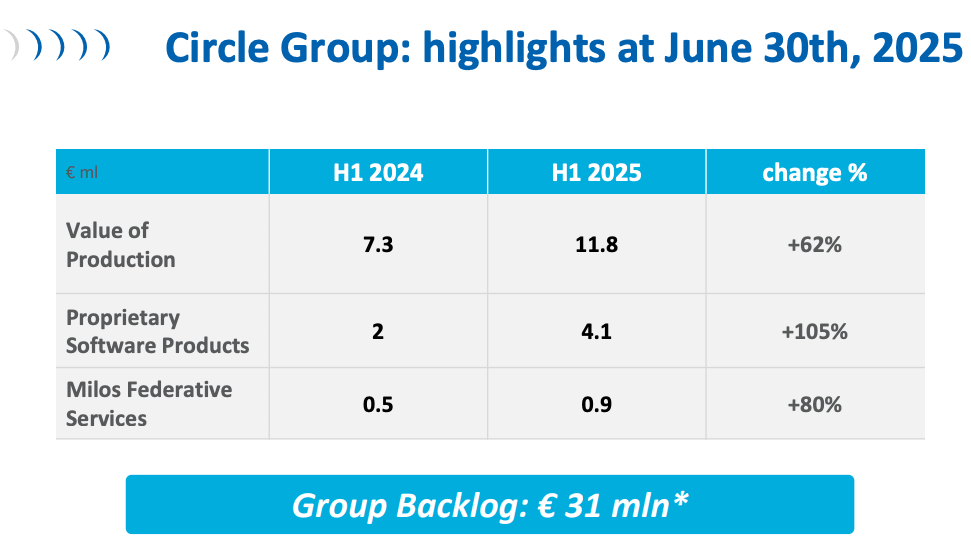
In the first half of 2025, Circle achieved revenues of EUR 9.7 million and a Value of Production (VoP, which includes other revenues & activated internal developments) of EUR 11.8 million (+62% yoy). Proprietary Software Products (license & recurring SaaS revenues) increased overproportionally by 105 % yoy and the Milos Federative Services (PPU) by 80%. Combined, these revenues with recurring characteristics accounted for 42% of the VoP in H1 2025.
The backlog of the group reached EUR 31 million.
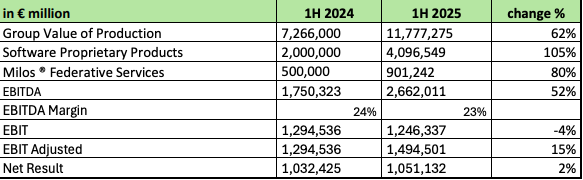
EBITDA reached EUR 2.7 million (+52%) in H1 with an EBITDA margin of 22.9 % (vs. 24.7 %). EBIT decreased by 4% yoy due to amortisations in relation to the re-organisation of exyond after the meaningful Telepass acquisitions.
Net income reached EUR 1.05 million (+2% yoy) of which EUR 0.03 million are related to third parties. So despite some acquisitions where Circle hasn’t bought 100% of the company, the vast majority of income (97% in H1) is related to the Circle Group and only 3% to third-party minorities.
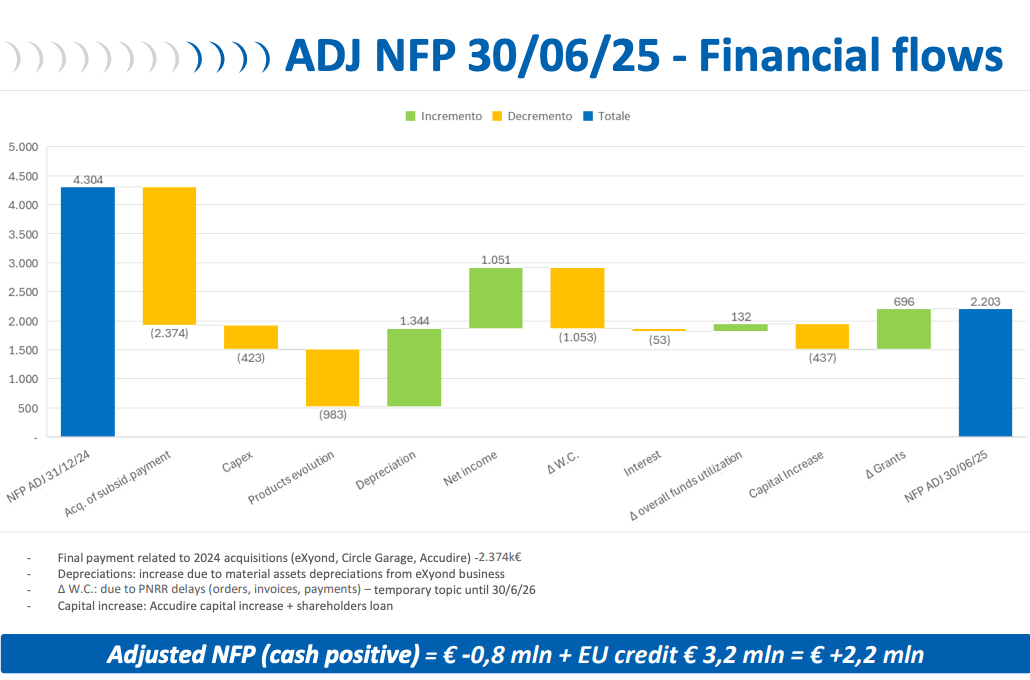
The company currently has a net debt of EUR 0.8 million, including EU credits they will receive they have net cash of EUR 2.2 million.
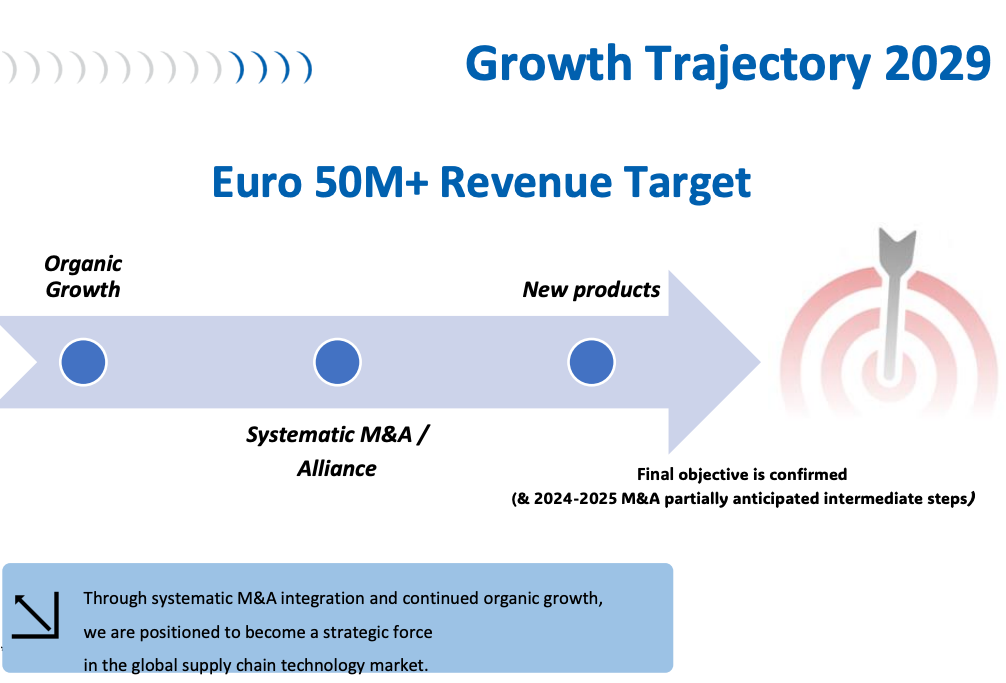
The long-term target of Circle is to reach revenues of EUR 50 million in 2029 through organic growth and systematic M&A integration.
9. Valuation
With the presentation of the H1 2025 results, Circle also increased the guidance for the full year, as well as for FY 2026. The management is now expecting VoP of EUR 24 - 26.4 million (prev. EUR 22.8 - 26.3 million).
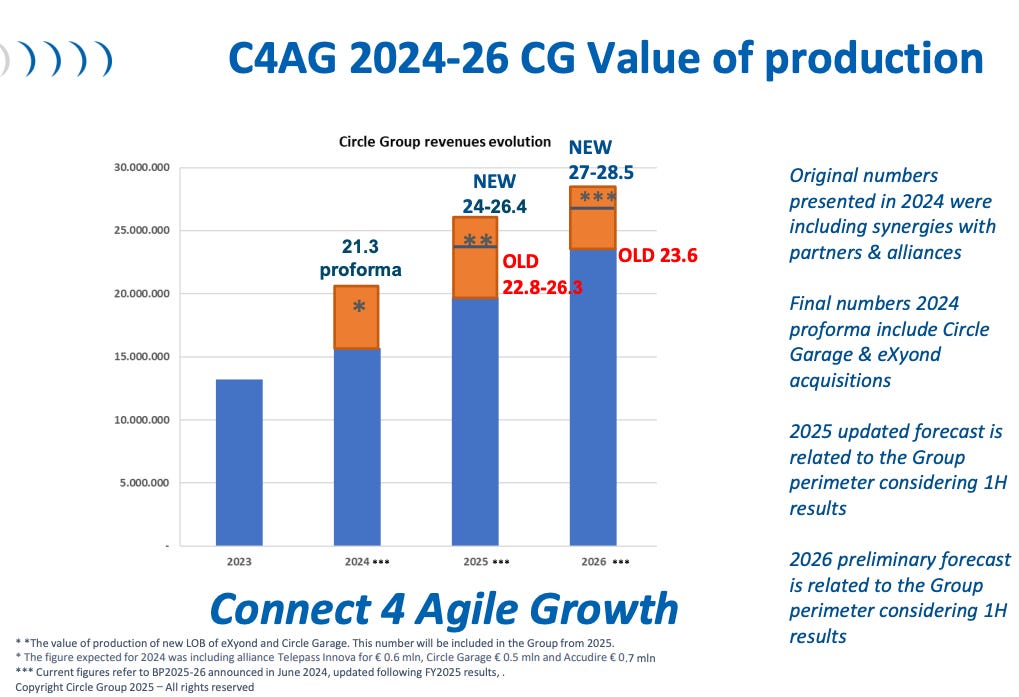
Compared to the pro forma VoP in 2024, this would imply growth of 12.7 % - 24 % in 2025 and in 2026 growth of around 10% in the midpoint of the guidance.
EBITDA is expected to increase even faster, with an EBITDA of EUR 5 - 5.7 million in 2025, implying growth between 16.3% and 32.6% and an EBITDA of EUR 6 - 7 million in 2026, implying growth of 21.5 % in the midpoint of the guidance.
If the company is reaching the midpoint of these guidance ranges, Circle currently trades at single-digit EV/EBITDA multiples for 2025 (8.2x) and 2026 (6.7x) as well as low double-digit EV/EBIT multiples for 2025 (16.4x) and 2026 (13.1x).
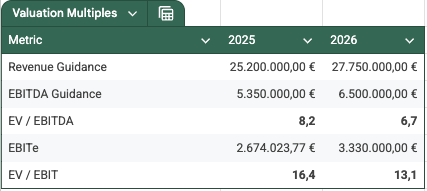
Even without further acquisitions, it is likely that Circle will be able to continue to grow by at least 10% in 2027, given that many EU digitization projects are multi-year projects and that many countries are just at the beginning of the process. If the trend to more recurring revenue models also continues, an EBITDA margin expansion to 24% and 14% seems also achievable in 2027, the EV/EBIT multiple for 2027 would be around 10x.
To achieve the target of EUR 50 million in revenues, further acquisitions will be needed. With the last, bigger acquisition of the Telepass Business Units at an EBITDA multiple of just 4.8x for a business with an EBITDA margin of 20% and a large part of recurring revenues, the management has shown that they are able to do value-creating acquisitions, even when this includes a dilution of existing shareholders.
The company has traded at lower multiples and in the past 3 years & the stock already increased by more than 100%. The higher multiple is at least partially deserved as the company has shown consistent organic growth in combination with value accretive acquisitions and an increasing share of recurring revenues since the IPO.
Below is a try of a peer group comparison. But with a market cap of only USD 52 million, Circle is obviously a very small company operating in a niche sector. So finding really good comparable companies that are also listed on a stock exchange is not easy. All the companies are in some parts comparable with some of Circle’s offerings, but I wouldn’t call one of them a real direct competitor, which makes the comparison quite difficult, but at least it gives a certain feeling of valuation multiples that are currently paid for these somewhat similar companies.
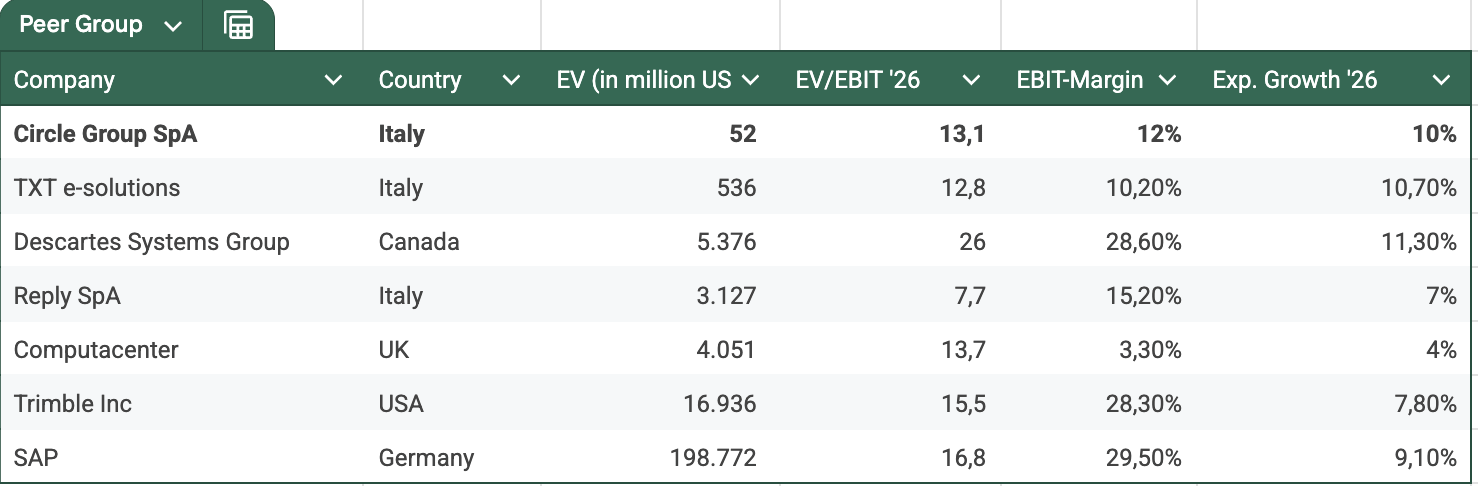
Circle is not stupidly cheap at the moment, but also not expensive. It seems to be somewhere between a fair valuation and a small undervaluation, which is of course dependend on the execution of the ambitious long-term targets of the company. At present, an initial starting position could be reasonable in order to observe further developments more closely, gain a feel for the company, and then eventually increase the position with a larger margin of safety if the price weakens and/or the company performs well.
10. Risks
Dependence on Regulation and Public-Sector Dynamics
A significant part of Circle’s growth thesis is linked to regulatory-driven digitalization, such as eFTI, customs reform, and port modernization. While regulation provides long-term demand visibility, it also introduces risk.
Implementation timelines can be:
delayed by political processes
fragmented across countries and regions
slowed by public procurement procedures
As a result, revenue realization may be uneven and lumpy, even when the strategic direction remains intact. Regulatory momentum does not always translate into short-term commercial execution.
Competitive Pressure from Larger Players
Circle operates in niches that are increasingly attracting attention from:
large logistics software vendors
ERP providers expanding into supply chain modules
international SaaS platforms offering visibility and compliance tools
While Circle benefits from domain expertise and regulatory knowledge, larger competitors may:
bundle solutions
price aggressively
leverage broader sales networks
This risk is particularly relevant in the global supply chain visibility segment, which is more competitive and less protected by regulation.
Execution Risk in Platform Integration and Acquisitions
Circle’s strategy includes integrating multiple platforms and selectively acquiring complementary businesses. While acquisitions have historically been small and strategic, they still carry risks:
integration complexity
cultural and technical alignment
management bandwidth
Failure to fully integrate platforms or extract expected synergies could dilute margins and distract from core execution.
Project-Based Revenue Volatility
Although Circle is gradually shifting toward recurring revenues, a meaningful share of revenues is still generated through:
implementation projects
consulting and integration work
public-sector-related contracts
This can lead to variability in quarterly or annual results, which may not always reflect the underlying long-term progress of the business.
Faster In-House Development by Customers with the help of AI
AI tools may enable large logistics players or operators to:
develop internal dashboards or optimization tools
automate document handling and data extraction
reduce reliance on external software for basic functionality
In theory, this could compress demand for standardized visibility or planning software. However, In customs, ports, and intermodal logistics, “working software” is not sufficient — it must be accepted by authorities and embedded in legal workflows, which is where Circle’s core value proposition lies.
Protectionism and Fragmentation of Global Trade
The gradual shift toward greater protectionism and fragmentation of global trade represents a structural risk for companies exposed to international logistics flows. Rising trade barriers, sanctions regimes, and regionalization of supply chains can lead to:
reduced cross-border trade volumes
increased uncertainty in global freight flows
postponed investment decisions by logistics operators
For Circle, this could translate into slower growth in transaction-based revenues and delayed implementation of discretionary digitalization projects, particularly those linked to international trade optimization rather than regulatory compliance.
At the same time, protectionism often increases regulatory complexity, rather than eliminating it. Additional customs procedures, reporting requirements, and compliance checks tend to raise the need for digital systems, especially in customs, documentation, and trade compliance.
11. Summary
Circle SpA stands at the intersection of digital transformation and essential logistics infrastructure. While the company operates in a niche that is not flashy, its work underpins the operational backbone of ports, intermodal hubs, and supply-chain participants across Europe. By focusing on mission-critical workflows and regulatory compliance such as eFTI-driven document digitalization, interoperability of freight systems, and customs modernization, Circle has positioned itself less as a discretionary software vendor and more as a provider of indispensable digital infrastructure.
This is reflected in an evolving revenue mix. Although legacy project and consulting work remains part of the business, there is a clear shift toward recurring contracts, cloud services, and usage-based models. These increasingly predictable revenue streams, including maintenance, SaaS subscriptions, and pay-per-use align with the gradual digital upgrade cycles typical of regulated logistics environments. As platforms like Milos® continue to gain traction, cross- and upselling within the existing installed base offers additional optionality for long-term value compounding.
However, investors should expect a gradual rather than exponential path to scale. Regulatory timelines, long sales cycles, public-sector procurement processes, and required integrations can make revenue recognition lumpy. The business might also face competitive pressure from larger supply-chain software vendors and potential shifts in geopolitics that can impact trade volumes.
Circle’s positioning in a structurally growing segment, combined with improving revenue quality and ecosystem integration, makes it a compelling consideration for investors willing to take a patient, long-term view.
Congrats!
You are one of the few who have actually read the write-up until the end. To say thank you, I am offering every survivor a 10% discount on the annual premium subscription, where you can see my full portfolio and get all the relevant news regarding these stocks.
Thanks for the great write-up. Circle SpA was on my to do list for quite some time !!
> its work underpins the operational backbone of ports, intermodal hubs, and supply-chain participants across Europe.
If so, why's ROIC ~ WACC (or even lower, and not just the latest FY)?